A practical guide for Australian business owners, accountants and advisers
If you have ever searched for the value of a business, you have probably encountered a deceptively simple formula:
| Business value = profit × industry multiple |
The arithmetic is easy. The difficult part is determining:
- Which measure of profit should be used
- Whether that profit is sustainable
- Which multiple is appropriate
- Whether the multiple produces an enterprise value or an equity value
- What adjustments must be made before arriving at the value of the shares or business interest
An “average industry multiple” may provide a broad reference point, but it is not automatically the correct multiple for your business. Two companies operating in the same industry—and reporting the same profit—can have materially different values.
The reason is simple: buyers do not purchase industries. They purchase individual businesses, with individual risks, opportunities, assets and dependencies.
Understanding business valuation multiples can help business owners assess offers, prepare for succession, resolve shareholder matters and make better strategic decisions. It can also prevent a convenient rule of thumb from being mistaken for a defensible valuation.
What Is a Business Valuation Multiple?
A business valuation multiple expresses value relative to a selected financial measure.
- Enterprise value divided by EBITDA
- Enterprise value divided by EBIT
- Enterprise value divided by revenue
- Equity value divided by net profit after tax
- Business value divided by seller’s discretionary earnings
For example, if a business produces maintainable EBITDA of $800,000 and an appropriate enterprise-value multiple is assessed at 4.5 times EBITDA:
| Indicative enterprise value = $800,000 × 4.5 = $3,600,000 |
That calculation is mathematically correct—but it is not yet a complete valuation. Before relying on the result, the valuer must establish that:
- $800,000 represents sustainable, maintainable EBITDA.
- EBITDA is the appropriate financial measure.
- The selected multiple is relevant to this particular business.
- The multiple and earnings measure are calculated consistently.
- Debt, surplus cash and other non-operating assets or liabilities are treated correctly.
- Any required adjustments for the ownership interest being valued are considered.
A multiple is therefore an input within a valuation method. It is not a substitute for the analysis supporting the valuation.
Why Do Business Valuers Use Multiples?
Multiples are commonly used because they connect a business’s financial performance with evidence about how buyers and investors price comparable businesses.
- Transactions involving comparable private businesses
- Acquisitions of businesses in the same or a related industry
- Trading multiples of comparable listed companies
- Previous transactions involving the subject business
- Other relevant market evidence
International Valuation Standards recognise market, income and cost approaches to valuation and require attention to the quality of the data, inputs, models, documentation and reporting used in an assignment. They also contain specific requirements for valuing businesses and business interests.
The concept is sound: if comparable businesses have sold for a certain relationship to earnings, that evidence may help indicate what the subject business is worth. The problem arises when the word comparable is treated too casually.
Why an Average Industry Multiple Can Be Misleading
An industry multiple generally combines evidence from several businesses or transactions. Those businesses may share an industry classification, but that does not make them economically equivalent.
- Size
- Profitability
- Growth
- Customer concentration
- Recurring revenue
- Management depth
- Owner dependence
- Geographic exposure
- Intellectual property
- Capital and working-capital requirements
- Debt
- Contract quality
- Regulatory risk
- Market position
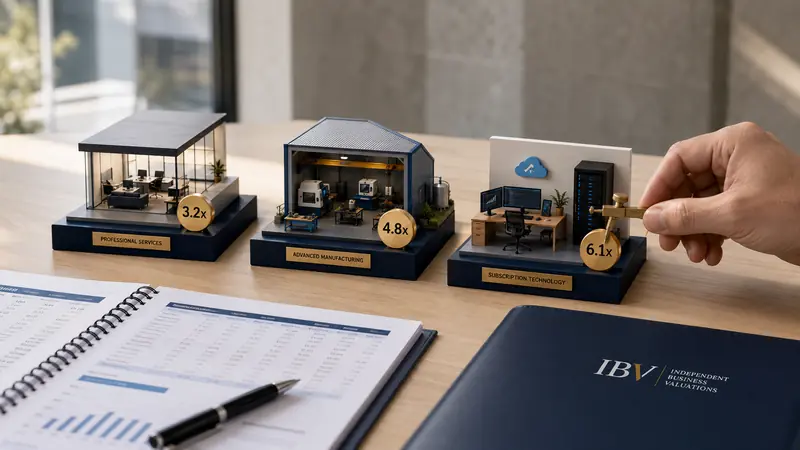
An average can conceal those differences. Imagine five transactions occurring at EBITDA multiples of 2.5, 3.0, 3.5, 5.5 and 7.0 times. The average is 4.3 times. But that does not establish that 4.3 is appropriate for the next business being valued.
The businesses at the upper end may have had long-term contracts, recurring revenue, proprietary technology and a management team capable of operating without the owners. Those at the lower end may have been highly founder-dependent, exposed to a few major customers or required significant reinvestment.
| The average describes the dataset. It does not explain where the subject business belongs within it. |
The Multiple and the Earnings Measure Must Match
One of the most common valuation errors is applying a multiple to the wrong financial measure.
EBITDA multiples
EBITDA means earnings before interest, tax, depreciation and amortisation. An enterprise-value-to-EBITDA multiple is intended to estimate the value of the operating business before allowing for its financing structure. It will therefore ordinarily produce an enterprise value, rather than the amount ultimately attributable to shareholders.
EBIT multiples
EBIT is earnings before interest and tax. Unlike EBITDA, it includes depreciation and amortisation expenses. An EBIT multiple may be more informative where depreciation reflects a genuine and recurring cost of consuming the assets required to operate the business.
Revenue multiples
Revenue multiples are sometimes used where earnings are temporarily low, inconsistent or not yet established. However, revenue alone says little about margins, operating efficiency or the capital required to generate sales. Two businesses may each produce $10 million in revenue, while one earns $2 million and the other barely breaks even.
Seller’s discretionary earnings multiples
Seller’s discretionary earnings are commonly discussed in relation to smaller, owner-operated businesses. The measure may add back an owner’s remuneration and certain discretionary expenses. Definitions are not always consistent, so a multiple derived from seller’s discretionary earnings should not be applied to EBITDA, EBIT or accounting profit without proper reconciliation.
Net-profit multiples
A multiple of net profit after tax may produce an equity value, depending on how the numerator and denominator have been defined. It should not be mixed indiscriminately with an enterprise-value multiple.
| The financial measure used in the multiple must be calculated on a basis consistent with the market evidence from which the multiple was derived. |
Reported Profit Is Not Necessarily Maintainable Profit
A valuation is generally concerned with the economic benefits a business can reasonably be expected to generate—not simply the profit reported in its latest financial statements. Historical earnings may require adjustment to estimate future maintainable earnings.
- One-off legal, consulting or restructuring costs
- Abnormal repairs or insurance recoveries
- Government grants that will not recur
- Personal or discretionary expenditure
- Related-party expenses above or below market rates
- Owner remuneration that differs from a commercial replacement salary
- Non-arm’s-length rent
- Revenue from a discontinued activity
- Unusually favourable or adverse short-term trading conditions
- Costs that a new owner would need to incur but which are currently absent
These adjustments must be supported by evidence. They should not become an exercise in removing every inconvenient expense or assuming that every positive development will continue. A valuation should explain what has been adjusted, the amount, why it is appropriate, whether it is genuinely non-recurring and how the result relates to expected future performance.
An overstated maintainable profit multiplied by an optimistic multiple compounds the error. Increasing earnings from $700,000 to $850,000 and the multiple from 4.0 to 5.0 changes the indicated value from $2.8 million to $4.25 million—a difference of $1.45 million.
What Determines the Right Business Valuation Multiple?
A multiple is, in effect, a compressed expression of expectations about risk, growth and future returns. All else being equal, buyers tend to pay higher multiples when future earnings appear more secure, transferable and capable of growth. They tend to pay lower multiples when those earnings are uncertain, concentrated or heavily dependent on the current owner.
1. Business size and earnings scale
Larger businesses may attract higher multiples because they can have greater management depth, more diversified revenue, better-developed systems and lower dependence on one individual. This is not automatic, and transaction evidence from substantially larger companies may require adjustment before it is relevant to a smaller enterprise.
2. Revenue quality
Contracted or recurring revenue may be viewed differently from revenue that must be won sale by sale. Contract duration, termination rights, renewal history, transferability and the extent of owner involvement all matter.
3. Customer concentration
A business deriving 40% of revenue from one customer carries a different risk from one with hundreds of unrelated customers. Contract duration, customer tenure, switching costs and whether the relationship belongs to the business or the owner should be assessed.
4. Owner dependence
Strong earnings can still be fragile when the founder controls sales, customer relationships, technical knowledge, pricing or staff. Owner dependence can influence the multiple, replacement-management costs, transition requirements and deal structure.
5. Growth and market outlook
Growth can support a higher multiple only when it is credible. Historical growth, current trading, order books, market demand, capacity, competition, funding needs and management’s ability to deliver should be examined.
6. Profit margins
Strong and stable margins may indicate pricing power, efficiency or differentiation. Unusually high margins also require investigation because they may reflect underinvestment, unpaid owner labour or costs not yet incurred.
7. Systems, management and scalability
Documented processes, delegated authority, experienced management, reliable reporting and protected intellectual property can support transferability. Growth that can use existing infrastructure may be more valuable than growth requiring costs to rise at the same rate.
8. Capital expenditure and working capital
EBITDA does not directly deduct capital expenditure or changes in working capital. Businesses with identical EBITDA may generate very different cash flows because of equipment, inventory, customer credit or technology requirements.
Enterprise Value Is Not the Same as the Seller’s Proceeds
A multiple of EBITDA or EBIT will commonly indicate enterprise value: the value of the operating business before considering how it is financed. A simplified bridge is:
| Enterprise value − interest-bearing debt + surplus cash ± other non-operating items = equity value |
If maintainable EBITDA is $800,000 and a 4.5-times multiple indicates enterprise value of $3.6 million, with $900,000 of interest-bearing debt and $250,000 of genuinely surplus cash, the simplified equity value is $2.95 million.
Even this may not equal the cash received at completion. A transaction may also involve working-capital adjustments, debt-like liabilities, inventory, transaction costs, tax, earn-outs, deferred consideration, vendor finance, retentions and warranties.
Public-Company Multiples May Not Fit a Private Business
Listed-company information is observable and can be useful, but listed corporations often have greater scale, diversification, management depth, access to finance, ownership liquidity, public disclosure and governance. A listed-company multiple should not simply be copied and applied to a private company. The characteristics of the subject company and the nature of the ownership interest must be considered.
Transaction Multiples Can Hide Important Deal Terms
A reported sale price may not reveal the full economics of a transaction. Announced consideration may include cash, deferred payments, earn-outs, vendor finance, assumed debt, retained ownership, employment arrangements, property or buyer-specific synergies. The earnings period used to calculate a reported multiple may also differ from the information considered by the purchaser. In private-company markets, incomplete information can limit the weight that should be placed on an apparently precise multiple.
Does the ATO Accept Business Valuation Multiples?
The Australian Taxation Office does not prescribe one universal multiple for each industry. Its market-valuation guidance emphasises selecting an appropriate methodology, using objective and supportable data, documenting assumptions and retaining evidence. The central question is not whether a multiple was used, but whether the valuation is supportable for its purpose.
An unsupported rule of thumb may be difficult to defend because it may not demonstrate the source and reliability of the multiple, the comparability of the underlying businesses, the calculation of maintainable earnings, the treatment of debt and cash, the valuation date or the reasoning connecting the evidence to the conclusion.
Worked Example: Same Industry, Same EBITDA, Different Value
Consider two businesses in the same industry. Each reports maintainable EBITDA of $1 million.
Business A
- Founder controls most customer relationships
- Largest customer represents 38% of revenue
- Revenue is largely project-based
- No second-tier management
- Limited documented systems
- Several key employees may leave with the owner
- Significant equipment expenditure is approaching
Business B
- Experienced management team operates the business
- No customer represents more than 8% of revenue
- Seventy percent of revenue is contracted or recurring
- Strong customer retention
- Documented systems and processes
- Consistent margins
- Modest capital-expenditure requirements
- Credible opportunities for expansion
Applying the same multiple to both would imply that their future earnings carry the same risk and transferability. They plainly do not. For illustration only, at 3.25 times EBITDA Business A indicates $3.25 million of enterprise value, while at 5.25 times Business B indicates $5.25 million.
The $2 million difference does not arise from current EBITDA. It arises from the expected durability, risk and transferability of future earnings. The example illustrates the principle; it does not prescribe either multiple.
Seven Questions to Ask When Someone Quotes an Industry Multiple
1. What is the source?
Actual transactions, listed companies, broker opinions, internal data or an unsupported rule of thumb?
2. What date does the evidence relate to?
Market conditions, interest rates, buyer appetite and industry outlook change.
3. How comparable are the underlying businesses?
Compare size, geography, margins, growth, concentration, revenue quality, management and capital requirements.
4. What earnings measure is being multiplied?
Reported EBITDA, normalised EBITDA, EBIT, revenue, net profit or seller’s discretionary earnings?
5. How were earnings normalised?
Every material adjustment should have a commercial basis and supporting evidence.
6. Does it produce enterprise value or equity value?
If enterprise value, how will debt, cash and other items be treated?
7. Has the conclusion been cross-checked?
A robust valuation may reconcile more than one relevant method rather than rely mechanically on a single calculation.
How to Make a Multiple-Based Valuation More Defensible
- Define the valuation purpose and date.
- Identify the interest being valued.
- State the basis of value.
- Analyse historical and current financial performance.
- Support the calculation of maintainable earnings.
- Explain the multiple evidence, comparability and limitations.
- Address entity-specific risks and opportunities.
- Show the bridge from enterprise value to equity value.
- Use appropriate cross-checks and sensitivity analysis.
- Disclose material limitations and uncertainty.
APES 225 establishes professional requirements for members of relevant Australian accounting bodies who provide valuation services, including requirements concerning scope, methodology, assumptions, reporting and disclosure. Although direct application depends on the practitioner’s professional status and circumstances, it is a useful reference point for disciplined valuation work.
What Business Owners Should Take From This
Business valuation multiples are useful. They make market evidence easier to interpret and communicate. But an average multiple is not a valuation conclusion.
| The better question is not “What multiple applies to my industry?” It is “What does the evidence indicate for a business with my company’s earnings quality, risks, growth prospects, management, customer base and capital requirements?” |
That distinction matters when preparing to sell, planning succession, transferring shares, buying out a shareholder, restructuring ownership, planning for tax, resolving a dispute or measuring how strategic improvements affect value. A properly prepared valuation does not eliminate judgement. It makes the judgement visible, evidence-based and capable of being tested.
An Industry Multiple Is a Starting Point—Not the Answer
The apparent simplicity of valuation multiples is attractive. But the simpler the formula, the more important the work behind its inputs becomes. A defensible multiple-based valuation requires analysis of sustainable earnings, market evidence, business-specific risk, growth, revenue quality, transferability, capital requirements, debt and cash, the ownership interest and the purpose and date of valuation.
Without that analysis, an “average industry multiple” can create an answer quickly—but not necessarily the right answer. If a major commercial, tax or ownership decision will rely on the valuation, the report should explain not only what the business is worth, but why the selected multiple is appropriate for that particular business.
Speak With Independent Business Valuations
Independent Business Valuations provides structured, evidence-based business valuation reports for business owners, accountants and advisers across Australia.
If you need to understand what your business may be worth—and why—IBV can help you obtain a clear, independent and defensible valuation.
| Discuss your business valuation with IBV → |
Primary sources and further reading
Australian Taxation Office — Market valuation for tax purposes https://www.ato.gov.au/law/view/document?DocID=SGM%2Fmarket_val&path=document
Australian Taxation Office — Market valuation of assets https://www.ato.gov.au/individuals-and-families/investments-and-assets/capital-gains-tax/market-valuation-of-assets
International Valuation Standards Council — International Valuation Standards https://ivsc.org/standards/
Accounting Professional & Ethical Standards Board — APES 225 Valuation Services https://apesb.org.au/wp-content/uploads/2024/10/APES_225_Oct_2024.pdf
Disclaimer: This article provides general information only. It is not financial, tax or legal advice and should not be relied upon as a valuation of any particular business.