BUSINESS VALUATION INSIGHTS
A practical guide to when an independent valuation becomes commercially important,
A Business Valuation Is Not Only for Selling a Business
Many owners first think about valuation when a buyer appears. By then, the valuation may be needed quickly, the information may not be ready and the owner may already be negotiating from an assumed number.
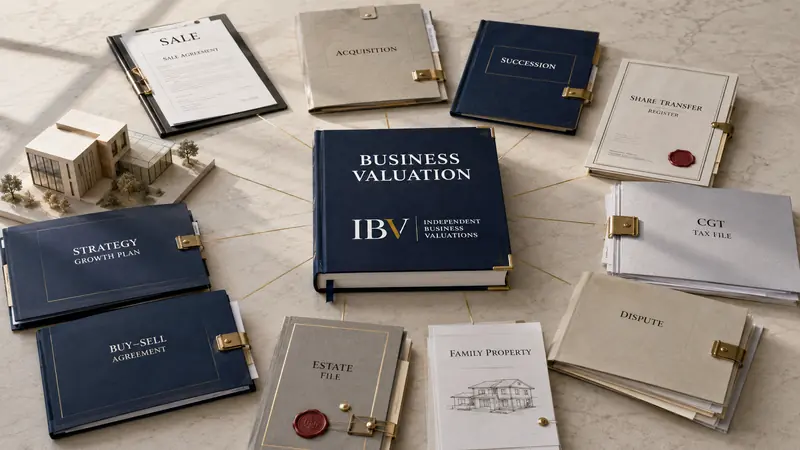
In practice, business valuations are used for ownership changes, succession, tax, disputes, family law, estate planning, insurance arrangements, employee equity and strategic decisions. The purpose matters because it affects the valuation date, the interest being valued, the standard and premise of value, the evidence required and the appropriate scope of work.
| Important distinction: A valuation is not automatically mandatory in every event below. Sometimes an agreement, law, regulator, court, lender or adviser requires one. In other cases, obtaining one is a commercial decision that replaces assumption with defensible evidence. |
What Does a Business Valuation Actually Establish?
A professional valuation estimates the value of a defined business, security or ownership interest at a specified date and for a specified purpose. It is not a permanent price tag.
The same business may have a different value at another date because earnings, risk, market conditions, capital requirements or available information have changed. Different purposes can also require different definitions or premises of value. That is why an old report—or a market appraisal prepared for another purpose—may not answer the current question.
1. Selling a Business or Assessing an Offer
A valuation can help an owner establish an evidence-based reference point before entering negotiations, appointing a broker or responding to an unsolicited offer. It can explain the maintainable earnings, risk factors, assets, liabilities and assumptions supporting the conclusion.
A valuation does not predict the exact sale price. Transaction prices can reflect buyer-specific synergies, finance, tax structure, warranties, deferred consideration, working-capital adjustments and negotiating leverage. The valuation instead provides a disciplined basis for evaluating whether an offer is commercially credible.
2. Buying a Business or an Ownership Interest
The buyer’s question is not merely whether the asking price matches an industry multiple. It is whether the expected earnings and cash flows justify the investment after considering risk, required working capital, capital expenditure, debt and the terms of the transaction.
An independent valuation can test assumptions and provide a separate value analysis. It does not replace financial, legal, tax, operational or commercial due diligence; those investigations may identify information that should change the valuation.
3. Succession or Transferring a Business Within the Family
A family transfer may involve competing objectives: rewarding the incoming generation, treating other beneficiaries fairly, protecting retirement funding and preserving the business. An unsupported figure can create tax risk, funding pressure or lasting family disagreement.
A valuation establishes a documented starting point for discussing price, gifting, staged transfers, funding and equalisation. It should be coordinated with legal, tax and financial advice, particularly where ownership and control will transfer at different times.
4. A Shareholder, Partner or Co-owner Is Entering or Leaving
When an owner joins, retires, resigns or must be bought out, the parties need to determine what interest is being transferred and how the relevant agreement calculates value. The result may depend on voting rights, distributions, restrictions, control, marketability and the contractual valuation mechanism.
The first step is to read the shareholders’ agreement, partnership agreement, constitution and any buy–sell provisions. A valuation should answer the question created by those documents—not substitute a generic concept of value.
5. Tax, CGT or a Business Restructure
Australian tax provisions may require or depend on market value in circumstances such as related-party transfers, changes in ownership, restructures and particular CGT events. The exact requirement depends on the transaction and applicable law.
The Australian Taxation Office states that taxpayers are responsible for providing objective and supportable evidence of market value where market value is required. For a complex asset such as a private business or shares, a documented valuation prepared for the relevant date is generally more defensible than reconstructing the evidence years later.
IBV provides the business valuation. Your accountant or tax adviser should determine the tax treatment, concessions and reporting requirements.
6. A Shareholder Dispute, Deadlock or Compulsory Exit
Disputes about control, distributions, conduct, access to information or an owner’s departure often become disputes about value. The relevant question may come from a contract, negotiated settlement, statutory remedy or court order.
A valuation can narrow the financial issue and make assumptions visible. In contentious matters, independence, instructions, evidence, valuation date and the valuer’s duty must be carefully managed. A preliminary commercial valuation is not automatically suitable as expert evidence in litigation.
7. Separation, Divorce or a Family-Law Property Matter
An interest in a private business may form part of the financial circumstances to be identified and assessed in a family-law property matter. The parties may agree on a jointly instructed expert, obtain advice about expert evidence or ultimately have disputed evidence tested by the court.
The appropriate scope depends on the legal instructions and procedural requirements. The valuation may need to distinguish business value from personal earning capacity, examine related entities and address the ownership interest actually held. Owners should obtain family-law advice before commissioning the report.
8. Estate Planning, Death or Administration of an Estate
Business interests can be central to a will, succession plan or deceased estate. A valuation may assist with equitable distributions, insurance adequacy, funding a buyout, administration decisions or establishing values relevant to tax and beneficiary discussions.
Not every inherited business interest receives the same tax treatment, and not every estate requires a formal valuation. However, where market value at a particular date affects cost base, allocation or a transaction between related parties, contemporaneous evidence can be important.
9. A Buy–Sell Agreement or Ownership-Protection Arrangement
A buy–sell agreement may be triggered by death, disability, trauma, retirement or another defined event. The agreement should specify what is valued, the valuation date, the method or process, who appoints the valuer and how insurance proceeds interact with the transfer price.
A formula written years earlier can produce an unintended result if the business has changed. Periodic valuation reviews can reveal a funding gap or a broken mechanism before a triggering event makes the problem urgent.
10. Strategic Planning, Value Improvement or Major Investment
A valuation can also be useful when no transaction is imminent. It can establish a baseline before a growth program, acquisition, management transition, capital investment or owner-exit plan.
The greatest benefit is not simply receiving a number. A well-explained valuation can identify what is supporting value, what is increasing risk and which assumptions have the greatest effect. A later valuation can then measure whether performance and risk have genuinely changed.
Other Situations Where a Business Valuation May Be Needed
Depending on the circumstances, a valuation may also assist with:
- employee share schemes or equity incentives;
- issuing, redeeming or transferring shares;
- financial reporting or impairment matters;
- insolvency, restructuring or creditor negotiations;
- insurance, loss or compensation claims;
- finance applications or covenant discussions; and
- regulatory, contractual or governance requirements.
Each context can involve different rules and evidence. A report prepared for one use should not be repurposed without checking whether the valuation date, definition, scope and assumptions remain appropriate.
When Is a Formal Business Valuation Required?
There is no single rule requiring every Australian business to obtain a valuation at a set interval or before every transaction. Whether one is required depends on the relevant tax provision, agreement, court process, accounting requirement, lender instruction, regulatory obligation or professional advice.
Even where a formal report is not mandatory, the commercial stakes may justify one. A useful decision test is whether the parties are relying on value to transfer wealth, allocate tax, settle a dispute, divide property, fund an exit or make an irreversible decision.
What Type of Valuation Report Do You Need?
The correct scope should be determined before the work begins. A comprehensive valuation engagement, a limited-scope engagement and a calculation engagement do not involve the same procedures or provide the same level of work.
The intended users and purpose should be explicit. A report for internal planning may not satisfy the requirements of the ATO, a court, an auditor, a lender or a contractual dispute. Choosing the cheapest scope before defining the purpose can result in a report that cannot be used.
What Information Will a Business Valuer Usually Request?
The information depends on the engagement, but commonly includes:
- historical financial statements, tax returns and current management accounts;
- details of owner remuneration, related-party transactions and proposed normalisation adjustments;
- budgets or forecasts and the assumptions supporting them;
- customer, supplier, employee and revenue-concentration information;
- material contracts, leases, licences and intellectual property records;
- debt, surplus assets, working capital and capital-expenditure requirements; and
- the relevant ownership documents, transaction terms or legal instructions.
Good information does not guarantee a higher value. It enables a clearer, more efficient and more defensible analysis.
How Early Should You Obtain a Business Valuation?
For a fixed valuation date—such as a tax event, separation, death or ownership transfer—the relevant date may already be determined. The report can sometimes be prepared later, but evidence is usually easier to obtain and test while it is current.
For succession, sale preparation or value improvement, earlier is generally more useful because the owner still has time to address concentration, owner dependence, records, contracts, management capability and other value drivers.
| Practical rule: Do not wait for the valuation to become the final obstacle in a transaction, dispute or succession plan. Define the purpose and required date as soon as value becomes material to the decision. |
Why Independence Matters
A valuation conclusion should follow the evidence and the selected methods—not the number preferred by a buyer, seller, shareholder or adviser. Independence is particularly important where the conclusion will affect tax, ownership, family interests or a dispute.
An independent report does not guarantee that every party will agree. It provides a transparent basis for understanding the subject interest, valuation date, evidence, assumptions, methods and conclusion.
The Bottom Line: Obtain the Valuation Before the Number Becomes the Dispute
A business valuation is most valuable when it answers a clearly defined question at the right time. It may support a sale, acquisition, succession, internal transfer, tax event, dispute, family-law matter, estate, buy–sell arrangement or strategic decision.
The common mistake is treating value as obvious until another party, adviser or authority asks for proof. By then, the evidence may be incomplete and the financial consequences may already be significant.
Independent Business Valuations provides fixed-fee, evidence-based valuation services to business owners and advisers Australia-wide. We provide the valuation; your legal, tax and financial advisers apply it to the broader decision.
| Discuss your valuation with IBV: Tell us what is happening, the interest involved, the required valuation date and who will rely on the report. We can then help define an appropriate valuation scope. |
Frequently Asked Questions About When You Need a Business Valuation
The following answers are general and should be considered alongside advice relevant to your circumstances.
Do I Need a Business Valuation Before Selling?
A valuation is not mandatory for every private sale, but it can provide an independent reference point for negotiations and help an owner understand the assumptions supporting value. It is different from a broker’s estimate of likely sale price.
Does the ATO Require a Professional Business Valuation?
The answer depends on the tax provision and transaction. Where market value is required, the ATO expects objective and supportable evidence. Complex business interests generally require more analysis and documentation than a simple estimate or unsupported multiple.
Can My Accountant Value My Business?
Some accountants provide valuation services and may be appropriately qualified and independent. The key questions are experience, scope, conflicts, evidence, reporting requirements and whether the report is fit for its intended purpose.
How Often Should a Business Be Valued?
There is no universal timetable. A new valuation may be appropriate when a material event occurs, the previous report has a different purpose or date, the business has changed significantly, or an agreement requires periodic review.
Can the Same Business Have Different Values?
Yes. Value can change with the valuation date, earnings, risk, market conditions and the interest being valued. Different standards or premises of value may also answer different questions. The basis must be stated rather than assumed.
Sources and Technical Basis
- Australian Taxation Office, Market valuation of assets
- Australian Taxation Office, Market valuation for tax purposes
- Australian Taxation Office, Cost base of inherited assets
- Federal Circuit and Family Court of Australia, Family-law practice directions and financial proceedings
- Accounting Professional & Ethical Standards Board, APES 225 Valuation Services (October 2024)
Editorial note: This article provides general information only. It is not legal, tax, accounting or financial advice. Whether a valuation is required, and the appropriate scope, depend on the specific event, governing documents, applicable law and intended use.