Key takeaways
IVS recognises market, income and cost approaches.
Market approaches use comparable evidence, income approaches convert future earnings or cash flows into value, and cost approaches consider replacement or reproduction cost. Practical asset-based methods assess assets less liabilities and are not automatically the formal cost approach.
Earnings capitalisation can suit businesses with sustainable profits.
It converts a sustainable level of earnings into a value using a capitalisation multiple that reflects risk and growth. Its reliability depends on how carefully earnings are normalised and how well the multiple is supported.
Discounted cash flow needs forecasts that can be defended.
DCF values projected future cash flows at a rate reflecting risk. It suits businesses with changing performance or long contracts, but only when the forecasts are reasonable and supported.
Asset-based methods offer an alternative indication, not an automatic floor.
These methods can be relevant for asset-intensive businesses, investment entities and weak earnings. Liabilities, realisation costs, tax, contractual restrictions and ownership rights affect whether net assets provide a meaningful alternative; they do not guarantee a minimum value.
A good valuation identifies the basis and explains its method selection.
No method is automatically best for every purpose or interest. A relevant secondary method is recommended where evidence permits, but multiple methods are not compulsory in every valuation; differences between indications should be explained.
Define the purpose and basis of value
Business valuation methods estimate value for a specified purpose and under a defined basis of value. Where market value is required, the assessment considers an exchange between informed, willing market participants at the valuation date. Investment value to a particular owner or a value determined under contractual terms may ask a different question. The report must identify the basis and the business or ownership interest being assessed before selecting methods.
The International Valuation Standards recognise three principal approaches:
In practical business valuation, asset-based methods are also commonly considered. Adjusted net assets assess the assets and liabilities individually; they should not automatically be equated with the formal cost approach. The assets themselves may require market, income or cost techniques.
The right choice depends on the business, the purpose of the valuation and the quality of the available evidence. A good valuer explains why the chosen method fits and considers a secondary method where relevant evidence permits; multiple methods are not required in every valuation.
Market approach: uses comparable transactions and other relevant market evidence.
Income approach: converts expected earnings or cash flows into present value, including capitalisation of maintainable earnings and discounted cash flow.
Cost approach: considers replacement or reproduction cost, with appropriate allowances for obsolescence.
Capitalisation of maintainable earnings
Capitalisation of future maintainable earnings is widely used for established, profitable businesses with reasonably sustainable earnings. Its suitability depends on the business, the available evidence and the purpose of the valuation. The idea is straightforward: identify the level of earnings the business can reasonably sustain, then apply a multiple that reflects the risk and growth prospects of those earnings.
Step one: maintainable earnings. The valuer starts with historical results, usually several years, and normalises them. That means adding back genuinely personal or one-off expenses, replacing owner wages with a commercial salary for the work actually done, adjusting related-party rent to a market level and removing unusual income. The aim is a figure a new owner could expect to repeat. Earnings may be measured before interest and tax (EBIT), before depreciation as well (EBITDA), or, for owner-operated businesses, as owner's discretionary earnings—the measure must match the multiple used.
Step two: the multiple. The capitalisation multiple reflects risk. Customer concentration, reliance on the owner, contract length, lease security, staff stability, industry conditions and growth prospects all push the multiple up or down. A market-derived earnings multiple draws on comparable transactions, whereas an independently developed capitalisation rate is built from supportable risk and growth assumptions. In a simple capitalisation model, the multiple is the reciprocal of the capitalisation rate. Their derivations differ, but both require evidence and consistency with the earnings measure; neither should be borrowed from a headline. Our article on EBITDA multiples explains why.
Step three: adjustments. Capitalising EBIT or EBITDA generally indicates an enterprise-level operating value; shareholder-level earnings can indicate equity value directly. Cash, non-operating assets, working capital and debt must be reconciled consistently with the selected value definition, without double-counting, before assessing the specified ownership interest.
This method is widely understood, works well when earnings are reasonably stable and is often a good fit for tax, family law and transaction purposes.
Discounted cash flow
A discounted cash flow (DCF) valuation projects the cash the business is expected to generate over a forecast period, adds a terminal value for the years beyond, and discounts everything back to the valuation date using a rate that reflects risk.
DCF suits businesses whose performance is expected to change materially—a business ramping up, winding down a contract or investing heavily—where a single maintainable earnings figure would not represent the future. It can also suit businesses with long, well-defined contracts.
Its weakness is its dependence on forecasts. Small changes to growth assumptions, margins or the discount rate can move the value significantly. A DCF is only as reliable as the forecasts behind it, which is why valuers test them against history, industry conditions and management's track record. Where reliable forecasts are not available, a DCF is usually not the primary method.

Signed
A clear valuation conclusion starts with an agreed purpose, relevant evidence and disclosed assumptions. The report identifies the interest valued and explains the reasoning behind its conclusion.
Asset-based methods
Asset-based methods value the business by reference to its assets less its liabilities. The two common versions are net assets on a going-concern basis and net realisable value on an orderly realisation or liquidation basis.
Asset-based methods are particularly relevant to asset-intensive businesses, investment entities and businesses with weak or unsustainable earnings. Net asset or realisation values may provide an important alternative indication, but they do not automatically establish a minimum value for every business or ownership interest. Liabilities, realisation costs, contractual restrictions, tax, liquidation assumptions and the rights attached to the interest can materially change the comparison. The ability and authority to realise assets also matter: a minority shareholder cannot necessarily require the business to sell its assets.
Asset values often need separate input. Property and specialised plant may require an independent property or plant valuer, and the business valuer will rely on and refer to that work.
Market approaches and rules of thumb
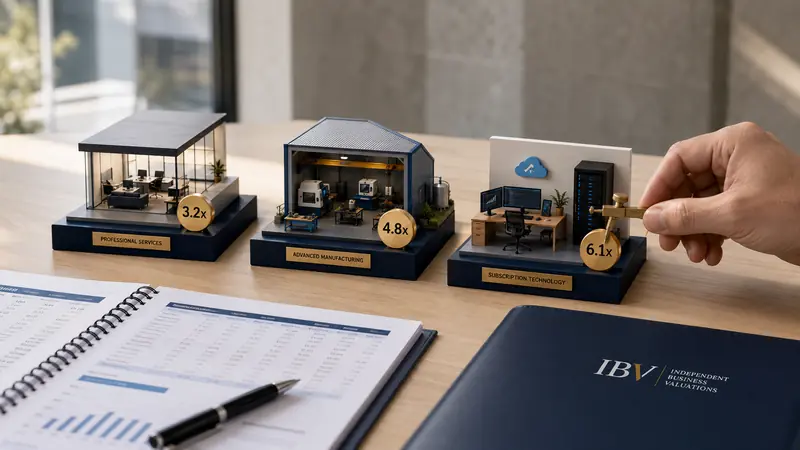
Market methods compare the business with prices achieved for similar businesses. In practice, reliable private-company transaction data in Australia is limited, and the details that matter—what was included, how the price was paid, the earnings definition used—are often unknown.
Industry rules of thumb, such as a multiple of fees for a practice or of annual income for a rent roll, fall into this category. They can be a useful cross-check and are sometimes how buyers in an industry talk about price. They are rarely enough on their own, because they hide differences in profitability, retention and risk between one business and the next.
How valuers choose and cross-check
Choosing a method starts with the purpose and the evidence. A tax valuation needs a method the ATO will recognise as appropriate; the ATO's market valuation guidance expects the valuer to explain the choice. A family law matter needs a method both parties can understand and test. A business with stable profits generally points to capitalised earnings; one with volatile prospects may point to a DCF; one with thin profits and substantial assets may point to an asset approach.
The ATO highly recommends a secondary methodology where possible. A cross-check should use relevant, reliable evidence rather than add a method merely to satisfy a checklist; IVS does not require multiple methods for every valuation. A capitalised earnings value can be tested against net assets, implied market multiples or a simplified DCF. When different perspectives agree, confidence grows; when they disagree, the valuer should explain why.
A simple worked illustration
This illustration is not a client matter and uses round numbers only to show the logic. A service business reports average profit of $420,000 over three years. The owner takes no salary, but a manager performing the owner's role would cost $140,000. One year includes a $40,000 insurance recovery that will not recur.
Assume the historical years are equally weighted, the insurance recovery is included in the reported average, the replacement management cost has not already been deducted and the profit measure is otherwise consistent with the selected multiple. The recovery must be removed from the three-year total before averaging, rather than deducting the entire recovery from each year's average.
The calculation uses unrounded earnings: ($420,000 − $140,000 − $40,000 ÷ 3) × 3 = $800,000. Applying 3× to the unadjusted average produces $1,260,000, a difference of $460,000. These fictional figures demonstrate the adjustments, not a recommended multiple for service businesses.
The example shows why normalisation and a justified multiple matter more than the arithmetic. It also shows why a cross-check is useful: if adjusted net assets indicated $900,000, the valuer would investigate the difference, confirm consistent asset and liability treatment and consider any realisation restrictions or costs. That alternative indication would not automatically replace the operating value or establish a floor for the particular shareholding.
Average annual reported profit: $420,000.
Annual replacement management cost: subtract $140,000.
One-off recovery in one historical year: $40,000; annualised deduction is $40,000 ÷ 3, approximately $13,333.
Normalised annual earnings: approximately $266,667.
Assumed capitalisation multiple: 3×.
Indicated operating value: approximately $800,000, before reconciling cash, non-operating assets, working capital and debt.
Methods and IBV™ engagements
IBV™ offers different levels of valuation engagement. A Calculated Value applies agreed calculation procedures, with the agreed method and limitations recorded in the Engagement Letter. A Limited Scope Conclusion of Value provides an independent conclusion within defined scope limitations; it is not subject to a universal one-or-two-method limit. A Full Conclusion of Value involves more extensive investigation and consideration of relevant methods, potentially including DCF where reliable forecasts are available. DCF is not mandatory for every comprehensive valuation. The appropriate scope, evidence requirements and methods are confirmed in the Engagement Letter. The Fixed Professional Fees page compares the three.
For a step-by-step guide to the whole process, read how to value a business in Australia. To discuss which method suits your business, book a Free Valuation Call.
Sources and further reading
Frequently asked questions
When does capitalisation of maintainable earnings suit a business?
Capitalisation of future maintainable earnings is widely used for established, profitable businesses with reasonably sustainable earnings. Its suitability depends on the business, purpose and reliability of the evidence, rather than a universal rule for Australian SMEs.
What are maintainable earnings?
Maintainable earnings are the level of profit a business can reasonably be expected to sustain, after normalising adjustments such as replacing owner wages with a commercial salary and removing one-off or personal items.
How is a capitalisation multiple chosen?
The multiple reflects the risk and growth prospects of the earnings. Customer concentration, owner dependency, contracts, lease security, staffing and industry conditions all influence it. A market-derived multiple and an independently developed capitalisation rate have different derivations. Both need support and must match the earnings definition; in a simple capitalisation model, the multiple is the reciprocal of the rate.
When is a discounted cash flow method appropriate?
DCF suits businesses whose future performance is expected to differ materially from the past, or that have long, defined contracts—provided reasonable, supportable forecasts are available.
When is an asset-based valuation used?
Asset-based methods can suit asset-intensive businesses, investment entities and weak or unsustainable earnings. Net asset or realisation values are alternative indications, not an automatic minimum. Liabilities, costs, tax, contractual restrictions and ownership rights affect the comparison.
Are industry rules of thumb reliable?
Rules of thumb can be a useful cross-check, but they hide differences in profitability, retention and risk between businesses. They are rarely a sufficient basis for a valuation on their own.
Should a valuation use more than one method?
The ATO highly recommends a secondary methodology where possible, but IVS does not require multiple methods in every valuation. Cross-checks need relevant, reliable evidence. Differences between indications should be investigated and explained rather than averaged mechanically.
Does the ATO prefer a particular valuation method?
The ATO does not prescribe a single method. It expects the valuer to select an appropriate method for the asset and purpose, explain the choice and support the inputs with evidence.
What is the difference between EBIT and EBITDA multiples?
EBITDA is earnings before interest, tax, depreciation and amortisation; EBIT deducts depreciation and amortisation. A multiple must be applied to the same earnings measure it was derived from, or the result will be distorted.
Which method does IBV™ use?
Method selection depends on purpose, scope and evidence. A Calculated Value applies agreed calculation procedures. A Limited Scope Conclusion of Value provides an independent conclusion within defined limitations, without a universal one-or-two-method limit. A Full Conclusion of Value involves more extensive investigation and relevant methods, potentially DCF where reliable forecasts exist. The Engagement Letter confirms scope.

A clear, independent view of value — with the evidence behind it.
- Understand the conclusion — and what drives value.
- Gain an independent perspective. Move forward with confidence.
- Benchmark your business against industry performance.
- Identify strengths, risks and opportunities through SWOT analysis.
WHAT YOU GET IN A LIMITED SCOPE VALUATION REPORT
Inside your IBV™ report
Executive Summary
Conclusion of value · Method selected · Valuer qualifications
Detailed Report
Maintainable earnings · Cap rate / multiple · Premise of value
The Evidence Pack
SWOT analysis · Top Performers Report · RAVDA score
APES 225 voluntarily aligned. Report depth and supporting analysis follow your agreed package and engagement scope.
Free Valuation Call