Key takeaways
Enterprise value is the business; equity value is what the owners hold.
Enterprise value measures the operating business regardless of funding. Equity value is what remains for owners after lenders' claims and adjustments for cash and assets the operations do not need.
Debt comes off, surplus cash goes on—but not all cash is surplus.
Bank loans, equipment finance and similar debt reduce equity value. Cash, debt and working capital must be reconciled consistently with the enterprise value definition: cash needed for normal operations should not be counted twice, while surplus cash and other non-operating assets may require separate adjustments.
Shareholder loans can move value between owners.
A loan you made to the company may reduce equity value, and whether it is repaid, assigned or left in place depends on the transaction terms. A loan the company made to you may increase equity value if it is recoverable and not already counted elsewhere.
A 50% shareholding is not automatically worth half the equity value.
The rights attached to the shares, ownership restrictions, marketability and the applicable valuation basis can materially influence the value of the individual interest, so halving a total equity figure is a starting point rather than a conclusion.
"Cash-free, debt-free" offers are enterprise value offers.
Compare a buyer's headline price with your net proceeds only after deducting the debt you must repay and allowing for working capital left behind. The report should show this bridge line by line.
Two different questions with two different answers
When someone asks "what is the business worth?", they may mean one of two things. Enterprise value is the value of the operating business as a whole—its ability to generate earnings from its customers, staff, systems and assets—regardless of how it is funded. Equity value is the value attributable to the owners after allowing for the claims of lenders and adjusting for assets the operations do not need.
Valuations based on EBIT, EBITDA or cash flow available to all providers of capital generally indicate enterprise value. Methods based on earnings or cash flows attributable specifically to shareholders may indicate equity value directly, and the report must clearly identify which measure is being concluded. Turning an enterprise-level figure into the value of your shares or units is a separate step, and skipping it is one of the most common reasons owners misunderstand a valuation, a sale offer or a buy-out price.
The Australian Government's guidance on valuing a business notes that valuation approaches look at earnings, assets and the market. Whichever approach is used, the report should be clear about which of these two values it concludes on.
Why enterprise value comes first
Two identical cafés can earn the same profit from the same customers in the same location. One has a $400,000 bank loan; the other has none. The business each owner operates is equally valuable—a buyer would pay much the same for either operation—but the owners do not hold equally valuable interests, because one owner owes the bank.
Separating the operating value from the funding structure lets a valuer compare businesses fairly and apply market evidence consistently. Funding is then dealt with explicitly, so nothing is counted twice and nothing is forgotten.
The bridge from enterprise value to equity value
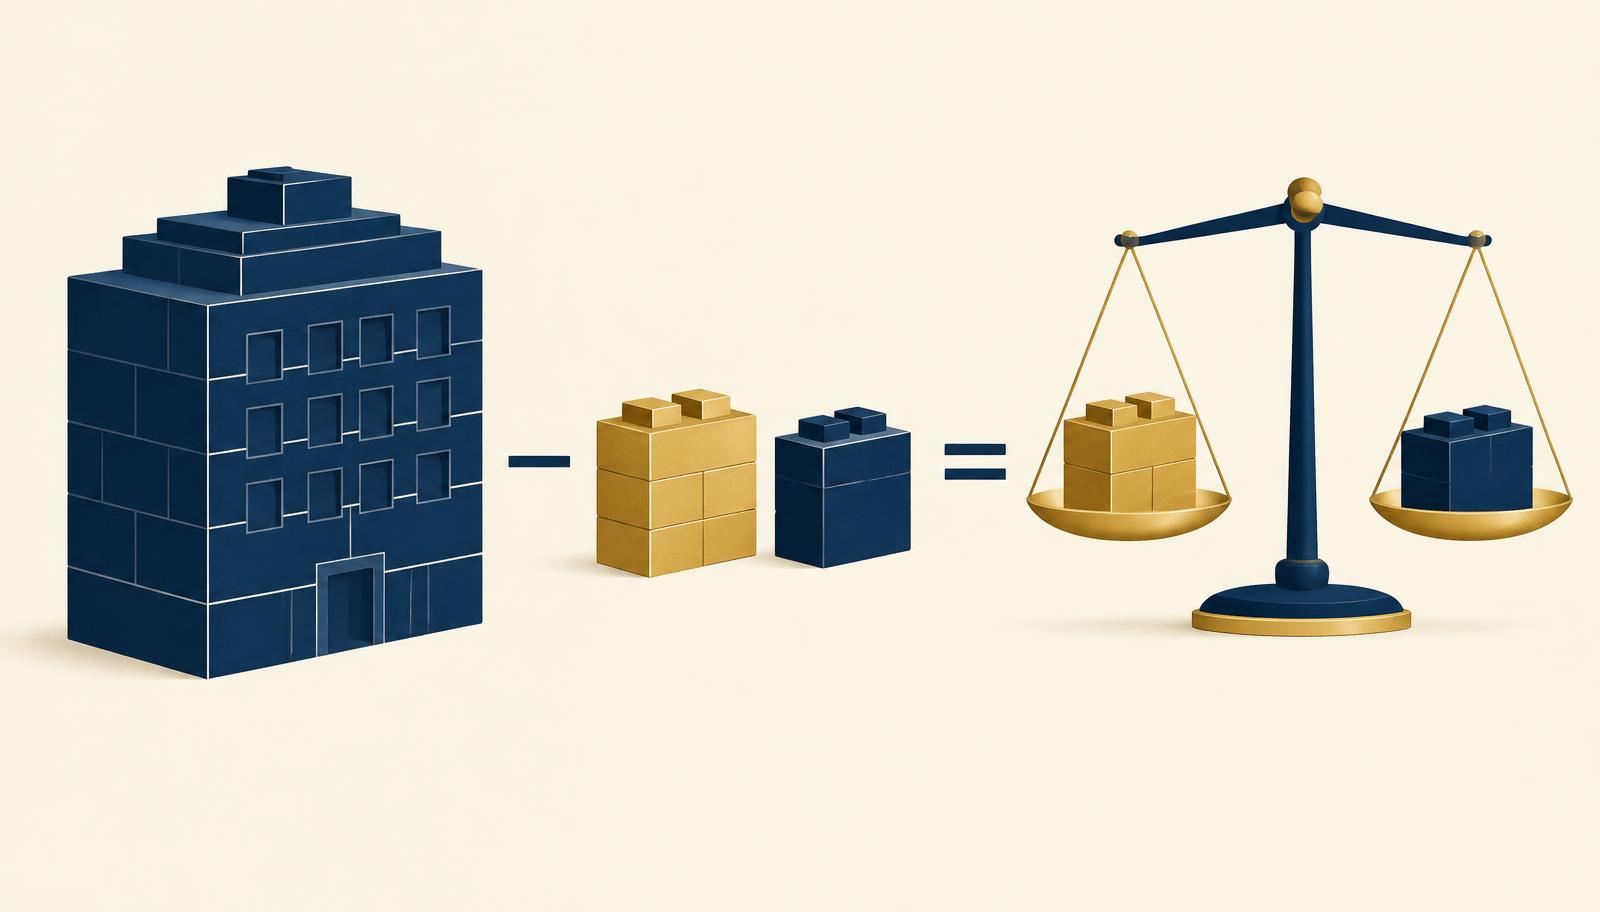
In simple terms:
Equity value = enterprise value − interest-bearing debt + surplus cash ± other adjustments
Each element needs evidence and judgement:
Interest-bearing debt includes bank loans, equipment finance, overdrafts, hire purchase and often lease liabilities, depending on how earnings were measured. Amounts owed to the ATO beyond normal trading terms may also be treated as debt.
Cash must be reconciled consistently with the enterprise value definition. Cash required for normal operations should not be counted twice, while surplus cash and other non-operating assets may require separate adjustments. Whether all cash or only surplus cash is added depends on how enterprise value and normal working capital have been defined.
Non-operating assets such as an investment property, a share portfolio or a vehicle used privately add to equity value but sit outside the operating earnings.
Working capital differences matter. If debtors, stock and creditors at the valuation date are far from their normal level, an adjustment may be required.

Signed
A clear valuation conclusion starts with an agreed purpose, relevant evidence and disclosed assumptions. The report identifies the interest valued and explains the reasoning behind its conclusion.
Shareholder loans and Division 7A balances
Loans between a company and its shareholders must be identified separately. A loan owed by the company may reduce equity value, while a shareholder loan receivable may increase it if recoverable and not already included elsewhere. Repayment arrangements, loan terms and any Division 7A consequences require separate consideration. These balances are common in Australian private companies and easy to misread.
Getting these balances wrong can shift the equity value by more than any debate over the earnings multiple. Our Division 7A valuation page explains when a valuation is needed for these arrangements.
A loan from you to the company is a liability of the company and may reduce equity value. It is not necessarily repaid on completion of a sale: repayment, assignment or continued existence depends on the transaction terms. In a sale, both the share price and the treatment of the loan need to be agreed.
A loan from the company to you is an asset of the company. Not every company loan to a shareholder is automatically a complying Division 7A loan: the statutory requirements and exceptions must be assessed. The ATO's Division 7A loan guidance confirms that loans potentially subject to Division 7A may need repayment or conversion to a complying arrangement by the applicable deadline to avoid deemed-dividend treatment. Whether the balance is genuinely collectable—and on what terms—affects how much value it contributes.
A worked example (fictional figures)
A fictional engineering company has normalised EBIT supporting an enterprise value of $2,000,000. Illustrative figures only.
Equity value: $1,500,000. A pro-rata 50% allocation would be $750,000, but the value of a specific 50% interest may differ depending on the rights attached to the shares and the applicable valuation basis. It is not $1,000,000, which is what many owners would assume by halving the business value.
The example assumes that every adjustment is separately identifiable, appropriately valued and not already reflected in enterprise value or another adjustment. The $150,000 owed to the founder is also a separate creditor interest: where that founder holds the 50% parcel, the loan claim sits alongside the shareholding rather than inside it.
Less bank loan: −$450,000
Less equipment finance: −$120,000
Plus surplus cash above the normal working float: +$180,000
Plus a loan owed by a shareholder to the company, assessed as collectable under its Division 7A agreement: +$90,000
Less a loan owed by the company to the founder: −$150,000
Less a working-capital shortfall against normal levels: −$50,000
Minority interests, control and the rights you actually hold
Equity value for the whole company is still not necessarily the value of your shares. A 25% holder usually cannot appoint the board, set dividends or force a sale; a 75% holder usually can. The shareholders' agreement or constitution may set out how shares are valued on exit, whether discounts for lack of control apply, and who may buy.
That is why a valuation must define its subject precisely—the whole business, all the shares, or a specific parcel—and the share and unit valuation service starts with those documents. The ATO's market valuation guidance similarly expects the interest being valued and its rights to be identified.
Where owners most often get caught
Comparing a sale offer to the wrong number. A buyer offering "$2 million on a cash-free, debt-free basis" is offering enterprise value. Your net proceeds depend on the debt you repay and cash you keep.
Assuming all cash is yours to take. The buyer will usually expect a normal level of working capital to be left in the business.
Forgetting shareholder loans. These can move money between owners in ways a simple percentage split ignores.
Treating property as part of the business. Premises owned inside the trading entity may need to be valued separately and the earnings adjusted for a market rent.
Working capital: the adjustment buyers negotiate hardest
Working capital is the money tied up in day-to-day trading. Debtors plus stock less creditors is a common shorthand, but other operating balances may also be relevant depending on the business and the agreed transaction definition. A business cannot earn its profits without it, so enterprise value assumes a normal level stays in the business.
Working-capital adjustments compare actual operating working capital with an appropriate normal level. Differences in debtors, inventory and creditors may affect equity value, but recoverability, cash movements and the treatment of each balance must be considered to avoid double-counting. Unusually high debtors do not automatically represent additional economic value—a late-paying customer can create a cash-flow problem and the receivable may be impaired—so higher receivables are assessed alongside cash balances and any doubtful debts before any adjustment is made.
The normal level is usually estimated from monthly balances over the past year or two, which smooths out seasonal swings. Retailers before Christmas, agricultural suppliers at harvest and builders near the end of a large project can all show balances that look very different from their average. In a sale, this becomes the "working capital target" or "peg" in the contract, and the price is adjusted up or down on completion for any difference. Owners who understand the concept before negotiating avoid a surprise reduction at settlement.
Property, investments and other non-operating assets
Assets that do not contribute to operating earnings sit outside enterprise value and are added separately at their own value. Common examples in Australian private companies include an investment property, surplus land, a share portfolio, cash held for a future project, or a holiday house owned by the company.
Premises used by the business need careful handling. Where a trading company owns its premises, one approach is to assess operating earnings after a supportable market rental charge and value the property separately, often with a report from a registered property valuer. The two components must then be reconciled consistently to avoid double-counting. The appropriate treatment depends on the valuation approach and the ownership interest being assessed, so it is not a mandatory calculation in every case. Our business and property valuation service coordinates both elements so they reconcile.
What a good valuation report shows
A clear report states which value it concludes on, shows the bridge line by line, explains the evidence for each adjustment, and identifies the rights attached to the interest valued. If the bridge is missing, ask for it: it is often the most useful page in the report for a sale, buy-out or restructure. For purposes where others will rely on the conclusion, a Limited Scope Conclusion of Value is usually the starting point; our Fixed Professional Fees page explains each engagement.
Frequently asked questions
What is the difference between enterprise value and equity value?
Enterprise value is the value of the operating business as a whole, independent of how it is funded. Equity value is the value attributable to the owners after deducting interest-bearing debt and adjusting for surplus cash, non-operating assets and similar items.
How do I calculate equity value from enterprise value?
Start with enterprise value, deduct interest-bearing debt such as bank loans and equipment finance, then adjust for cash, non-operating assets, working capital and shareholder loans. Each item needs evidence at the valuation date, and every adjustment must be reconciled consistently with the enterprise value definition so no component is counted twice.
Is all the cash in the business bank account added to the value?
Not automatically. Whether all cash or only surplus cash is added depends on how enterprise value and normal working capital have been defined. Cash needed for payroll, suppliers and seasonal trading should not be counted twice, while genuinely surplus cash and other non-operating assets may be added separately.
How are shareholder loans treated in a business valuation?
A loan from a shareholder to the company is a liability that may reduce equity value, though repayment, assignment or continued existence depends on the transaction terms. A loan from the company to a shareholder is an asset that may increase equity value if recoverable and not already included elsewhere. Repayment arrangements, loan terms and any Division 7A consequences require separate consideration.
Source: ATO: Division 7A loans
Does a Division 7A loan affect the value of my shares?
It can. A complying Division 7A loan owed to the company is generally an asset of the company, but its value depends on its terms and collectability. A non-complying loan can also have tax consequences your adviser should address.
Source: ATO: Division 7A loans
What does a cash-free, debt-free offer mean?
It means the buyer's price is for the operating business, assuming you repay debt and keep surplus cash. It is effectively an enterprise value offer, usually with a requirement to leave a normal level of working capital.
Is my 50% share worth half of the business value?
Not automatically. A 50% shareholding does not necessarily have a market value equal to half the total equity value. Its value may depend on voting rights, deadlock provisions, marketability, transfer restrictions and the applicable valuation basis.
Are lease liabilities treated as debt?
Sometimes. It depends on how the earnings were measured. If rent was excluded from earnings, lease liabilities may be treated like debt; if rent was deducted in earnings, they usually are not. The report should apply one consistent approach.
Which value does the ATO look at?
It depends on the asset. For a transfer of shares, the market value of the shares—an equity-level value of the specific interest—is usually relevant. The ATO's guidance expects the interest and its rights to be identified clearly.
Should my valuation report show both values?
Where the purpose involves shares, units or a sale, yes. Showing enterprise value and the bridge to equity value makes the conclusion transparent and lets your advisers check each adjustment.
Source: APESB: APES 225 Valuation Services (IBV™ aligns voluntarily)

A clear, independent view of value — with the evidence behind it.
- Understand the conclusion — and what drives value.
- Gain an independent perspective. Move forward with confidence.
- Benchmark your business against industry performance.
- Identify strengths, risks and opportunities through SWOT analysis.
WHAT YOU GET IN A LIMITED SCOPE VALUATION REPORT
Inside your IBV™ report
Executive Summary
Conclusion of value · Method selected · Valuer qualifications
Detailed Report
Maintainable earnings · Cap rate / multiple · Premise of value
The Evidence Pack
SWOT analysis · Top Performers Report · RAVDA score
APES 225 voluntarily aligned. Report depth and supporting analysis follow your agreed package and engagement scope.
Free Valuation Call