Two businesses report the same annual profit. One attracts strong buyer interest and a premium valuation. The other struggles to find a buyer except at a substantial discount.
How can that happen?
Because profit is only part of the valuation equation.
A buyer is not purchasing last year’s profit in isolation. The buyer is assessing the future economic benefits the business may generate, the investment required to produce them and the risk that they will not be achieved. The durability, transferability and growth potential of earnings can therefore matter as much as the amount reported in the accounts.
This is where business value drivers become important. Value drivers are the financial, operational and commercial characteristics that influence expected returns and risk. Some are visible in the profit and loss statement. Others—such as customer concentration, owner dependence, management depth and the quality of systems—may be less obvious but highly relevant to a professional valuation.
This guide explains 12 of the most important business value drivers, how they affect valuation analysis and what Australian business owners can do to build a stronger and more transferable business.
Why Can Two Businesses With the Same Profit Have Different Values?
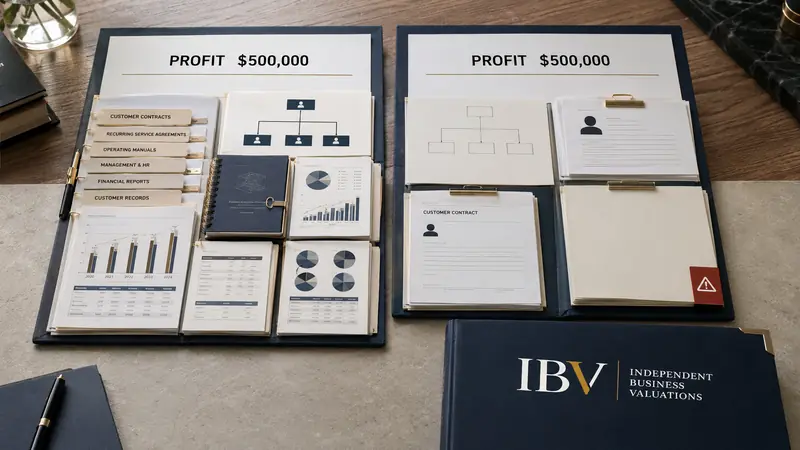
Imagine two companies each reporting $500,000 of profit.
The first has contracted recurring revenue, hundreds of customers, a capable management team and documented operating systems. No individual customer represents a material proportion of sales, and the owner can take extended leave without disrupting operations.
The second depends on three major customers and the owner personally controls sales, pricing, supplier relationships and key technical knowledge. Revenue must be won again each month, financial records require extensive adjustment, and the business has no credible management succession.
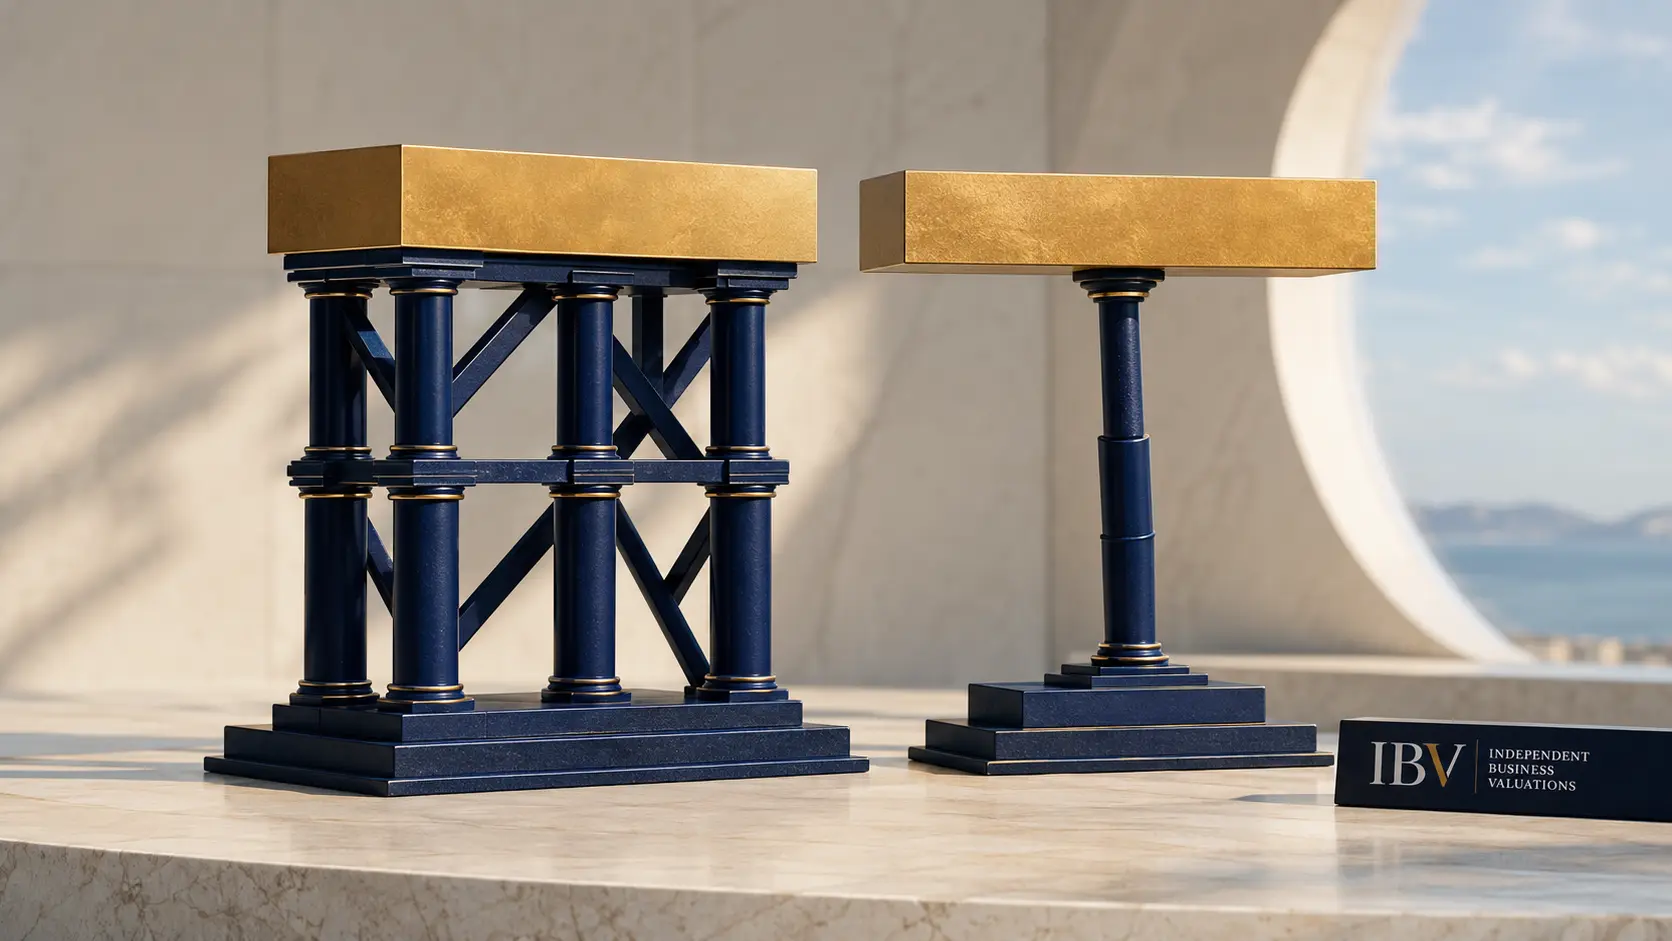
The historical profit is the same. The risk surrounding the continuation and transfer of that profit is not.
All else being equal, a buyer may be prepared to pay more for the first business because its earnings appear more sustainable, transferable and predictable. The second business may require a higher return to compensate for greater uncertainty—or the buyer may decline to proceed altogether.
A professional valuation therefore looks beyond the headline profit figure. It considers questions such as:
- Are the reported earnings maintainable?
- How predictable is future revenue?
- How dependent is the business on its owner, key employees or major customers?
- What capital and working capital are required to sustain operations?
- Can the business transfer successfully to a new owner?
- What evidence supports the forecast growth?
The answers help explain why an apparently small operational weakness can have a meaningful effect on value.
How Do Business Value Drivers Affect a Business Valuation?
Value drivers do not operate through a universal scoring system. There is no defensible rule that says reducing owner dependence automatically adds a particular percentage to value, or that recurring revenue always produces a specified valuation multiple.
Instead, value drivers influence the assumptions and evidence used within the selected valuation approach.
Under an income approach, for example, risk may be reflected in the capitalisation rate or discount rate, while sustainable growth, required reinvestment and expected cash flows affect the economic benefits being valued. Under a market approach, the characteristics of the subject business influence how comparable transactions are selected, interpreted and adjusted. Under an asset approach, the nature, condition and economic usefulness of assets—and the recognition of liabilities—become particularly important.
International Valuation Standards identify market, income and cost approaches as principal valuation approaches and include a dedicated asset standard for businesses and business interests. Australian Government guidance similarly recognises that there is no single method appropriate for every business and that a combination of methods may be used.
The critical point is that a valuation multiple is not an independent fact floating above the business. It is a compact expression of expectations about return, risk and growth. Applying an “industry multiple” without analysing the underlying business value drivers can therefore produce a result that appears precise but is poorly supported.
The 12 Business Value Drivers That Can Influence What a Business Is Worth
The relative importance of each driver depends on the business, industry, ownership interest, valuation purpose and valuation date. The following 12 drivers are not a mechanical checklist; they provide a practical framework for understanding what supports—or constrains—business value.
1. Maintainable Earnings and the Quality of Profit
Valuers do not simply accept the latest accounting profit as the economic return available to an owner. They commonly analyse historical results and consider adjustments needed to estimate maintainable earnings.
Potential adjustments may include:
- non-commercial owner remuneration;
- personal or discretionary expenses;
- related-party transactions that are not on market terms;
- exceptional, non-recurring income or costs;
- discontinued activities;
- unusual repairs, legal expenses or insurance recoveries; and
- costs a buyer would need to introduce after acquisition.
The direction of an adjustment is not automatically favourable to the seller. Removing a one-off expense may increase adjusted earnings, but adding a commercial management salary or previously deferred expenditure may reduce them.
Quality also matters. Earnings supported by consistent operating performance and reconciled records are more persuasive than earnings produced by aggressive adjustments or a single exceptional year. A business owner seeking to improve value should focus not only on generating profit, but on making the sources of that profit transparent and repeatable.
2. Recurring Revenue and Revenue Predictability
Revenue that is contracted, subscribed, retained or otherwise repeatable can improve visibility over future performance. This does not mean all recurring revenue is equally valuable. The strength of the underlying arrangements still needs to be assessed.
Relevant questions include:
- What proportion of revenue is genuinely recurring rather than merely historically repeated?
- How long are the contracts and when can customers terminate?
- What are renewal, retention and churn patterns?
- Are prices fixed while delivery costs can rise?
- Does revenue depend on the owner’s ongoing personal relationship?
- Are there service obligations or deferred costs attached to the revenue?
A written contract with weak economics or easy termination may offer less protection than its label suggests. Conversely, a business without formal subscriptions may still demonstrate dependable repeat purchasing through strong customer retention data.
The value driver is not the phrase “recurring revenue.” It is credible evidence that revenue and the associated margin are likely to continue.
3. Customer Concentration and Customer Retention
A large customer can be commercially attractive while also creating concentration risk. If the loss of one customer would materially reduce earnings, cash flow or operational efficiency, a buyer will want to understand the strength and duration of that relationship.
The analysis may consider:
- revenue and gross profit by customer;
- contract terms and termination rights;
- length of relationship;
- customer retention and churn;
- the customer’s financial strength;
- whether relationships belong to the business or primarily to the owner; and
- how readily lost revenue could be replaced.
Concentration is not assessed by revenue percentage alone. A stable government contract, a diversified group of related customers and an informal arrangement with one privately owned customer present different risks even if each contributes the same proportion of sales.
Reducing excessive concentration can make earnings more resilient. Where diversification is not immediately practical, stronger contracts, documented account management and evidence of renewal history may at least help a reader understand the risk more accurately.
4. Owner Dependence and Key-Person Risk
Many successful private businesses are built around the founder’s skill, reputation and relationships. That can be a source of competitive strength while the owner remains—but a transfer risk when the owner leaves.
Owner dependence may exist where the owner personally controls:
- major customer and supplier relationships;
- sales and pricing decisions;
- technical knowledge or intellectual property;
- employee supervision;
- financial approvals;
- quality control; or
- the reputation under which work is won.
The central valuation question is whether the business’s earnings can continue under new ownership. If the buyer must replace several roles performed by one underpaid owner, maintainable earnings may need to reflect the full commercial cost of those functions. If important goodwill is inseparable from the individual, its transferability may also be questioned.
Reducing owner dependence does not mean making the owner irrelevant. It means converting personal capability into organisational capability through delegation, systems, employment arrangements, customer ownership and documented knowledge.
5. Management Depth and Workforce Capability
A capable management team can give a buyer confidence that operations will continue after a change of ownership. Management depth is particularly important when the owner intends to exit quickly or when growth requires skills beyond the founder’s capacity.
A valuer or buyer may consider:
- whether important functions have accountable leaders;
- the experience and tenure of management;
- employee turnover and vacancies;
- remuneration and retention arrangements;
- succession for key roles;
- reliance on contractors or scarce specialist skills; and
- whether employment agreements protect confidential information and intellectual property.
A large workforce is not necessarily a strong workforce. What matters is whether the right capabilities exist, responsibilities are clear and the organisation can operate through normal staff changes.
Investment in management may reduce short-term profit before it supports longer-term value. That trade-off illustrates why maximising this year’s accounting result is not always the same as building the strongest business.
6. Documented Systems, Processes and Business Data
Systems make performance more repeatable. They also allow a buyer to understand how the business operates without relying entirely on the seller’s memory.
Useful documentation may include:
- standard operating procedures;
- pricing and quotation controls;
- customer onboarding and service processes;
- quality assurance and compliance records;
- financial delegations;
- cybersecurity and data-management controls;
- employee training materials; and
- management reporting routines.
Documentation alone is not enough. A procedure that is out of date or ignored by staff provides limited comfort. Strong systems are embedded in day-to-day operations, supported by appropriate technology and evidenced through reliable data.
Australian Government succession guidance specifically recommends documenting policies, procedures and processes so vital knowledge does not leave when the owner exits. From a valuation perspective, effective systems can support transferability, scalability and reduced operational risk.
7. Growth Prospects and Scalability
Buyers pay for expected future benefits, not aspiration alone. A credible growth opportunity can support value when there is evidence that the opportunity is achievable and economically attractive.
Questions may include:
- Is demand growing in the addressable market?
- Does the business have a realistic sales pipeline?
- Can capacity expand without costs increasing at the same rate?
- What people, systems, premises and capital are required?
- Are forecast margins consistent with operational reality?
- Does growth increase working-capital pressure?
- What competitors or regulatory constraints may limit expansion?
Growth can destroy value if it consumes cash, creates uncontrolled risk or produces inadequate returns. A forecast showing rapid revenue growth is therefore not automatically valuable. The assumptions, investment requirements and execution capability must be supportable.
Scalability is strongest where additional revenue can be delivered without proportionate increases in cost or complexity. However, every business has constraints. A credible plan recognises them rather than assuming they disappear.
8. Competitive Advantage, Brand and Intellectual Property
A business may earn superior returns because it offers something customers value and competitors cannot readily replicate. That advantage might arise from brand, reputation, intellectual property, proprietary data, location, licences, distribution, network effects, specialised knowledge or cost efficiency.
The strength of a competitive advantage depends on evidence:
- Does it support pricing, margins or customer retention?
- Is it legally protected where protection is available?
- Does the company own the intellectual property it uses?
- Can competitors reproduce it at reasonable cost?
- Is the advantage tied to the current owner?
- How long is it likely to remain relevant?
Accounting balance sheets often do not recognise internally generated brands, customer relationships or goodwill as assets. Their absence from book value does not mean they lack economic value. Equally, describing something as “intellectual property” does not establish that it is protected, transferable or commercially valuable.
9. Cash Flow, Working Capital and Capital Expenditure
Profit is not cash. A growing business can report strong earnings while absorbing cash through inventory, debtors, equipment or other investment.
Important considerations include:
- how quickly customers pay;
- supplier payment terms;
- inventory levels and obsolescence;
- seasonal working-capital requirements;
- recurring replacement capital expenditure;
- deferred maintenance;
- lease commitments; and
- the conversion of accounting profit into cash flow.
Two businesses with the same earnings may require very different amounts of capital to sustain those earnings. A buyer will generally prefer, all else being equal, a business that converts profit into cash reliably and does not require disproportionate reinvestment.
Working capital also affects transaction structure. Sale agreements commonly define the level of working capital to be delivered at completion, while debt, cash and surplus assets may be treated separately in moving from enterprise value to equity value. These matters should be defined rather than assumed.
10. Supplier, Employee and Operational Concentration
Customer concentration receives considerable attention, but dependence elsewhere in the operating model can be equally important.
A business may rely upon:
- one supplier or manufacturer;
- a single licence, lease or distribution agreement;
- one key employee or subcontractor;
- one facility, system or piece of equipment;
- one marketing channel or referral source; or
- one jurisdiction or regulatory approval.
The relevant issue is the consequence of failure and the availability of alternatives. A sole supplier may be manageable if a tested substitute is readily available. Dependence on a scarce input controlled by a competitor may be far more serious.
Business continuity plans, alternative suppliers, cross-training, appropriate insurance and tested recovery procedures can reduce exposure. They do not eliminate every risk, but they may demonstrate that management understands and actively controls it.
11. Financial Reporting, Controls and Information Quality
A buyer or valuer cannot analyse what the records do not reliably show. Poor information creates uncertainty, slows due diligence and may weaken confidence in reported earnings.
Useful financial information commonly includes:
- reconciled financial statements and tax returns;
- current management accounts;
- revenue and margin analysis by product, service or customer;
- aged receivables and payables;
- inventory records;
- budgets and forecasts compared with actual performance;
- details supporting proposed earnings adjustments; and
- clear separation of business and personal expenditure.
Clean records do not create value independently of commercial performance. They make the performance easier to verify, explain and monitor. Conversely, unexplained discrepancies may cause a buyer to adopt more conservative assumptions or require additional protections.
APES 225 requires members of CA ANZ, CPA Australia and IPA providing valuation services to gather sufficient and appropriate evidence to provide reasonable grounds for the report and its conclusions. Although APES 225 does not formally govern non-members, the underlying principle is commercially important: a valuation conclusion should be supported by evidence, not assertion.
12. Transferability and Transaction Readiness
Value is ultimately affected by what can be transferred and on what terms. A profitable activity may be difficult to sell if the necessary contracts, licences, intellectual property, people or relationships cannot move to a buyer.
Transaction readiness may involve reviewing:
- ownership of shares, assets and intellectual property;
- shareholder, partnership and trust documentation;
- customer and supplier assignment clauses;
- premises and equipment leases;
- employment and contractor arrangements;
- licences, permits and regulatory approvals;
- unresolved disputes and contingent liabilities;
- related-party balances and transactions; and
- the separation of surplus or non-operating assets.
This is not a substitute for legal, tax or transaction advice. It is recognition that the asset being valued must be clearly identified and capable of being dealt with in the proposed transaction.
A business can be commercially attractive but transactionally unprepared. Resolving ownership, documentation and consent issues before entering negotiations can reduce delay, uncertainty and the risk of a failed sale.
Enterprise Value vs Equity Value: Why Debt and Surplus Assets Matter
Business owners often hear a multiple applied to earnings and assume the result is the amount they will receive. That can confuse enterprise value with equity value.
In simplified terms, an earnings-based calculation may first indicate the value of the operating business before considering how it is financed. Moving from that enterprise value to the value attributable to equity may require consideration of debt, cash, surplus assets, non-operating liabilities and the required level of working capital.
The exact treatment depends on the valuation basis and transaction terms. Not every balance-sheet item is simply added or deducted at face value, and definitions of “debt” or “debt-like items” can become important in a sale agreement.
This is another reason two companies with the same profit and the same operating multiple may not produce the same value for shareholders.
How Can Business Owners Improve Their Business Value Drivers?
Improving value is usually a management program, not a last-minute presentation exercise. Cosmetic changes made immediately before a valuation are less persuasive than a sustained record of improved performance and reduced risk.
A practical approach is to:
- Establish the current position. Identify the earnings, risks and operational dependencies that currently drive value.
- Prioritise material issues. Focus on weaknesses that genuinely threaten earnings, transferability or growth—not a generic list of improvements.
- Assign responsibility. Give each initiative an owner, budget, timeframe and measurable outcome.
- Build evidence. Track retention, concentration, margins, cash conversion, forecast accuracy and other relevant indicators.
- Review progress consistently. Distinguish actual improvement from changed assumptions or a favourable short-term result.
The goal should not be to manufacture a higher valuation. It should be to build a better business whose stronger economics and lower risks can be demonstrated.
Some improvements may reduce profit initially. Hiring management, upgrading systems, securing intellectual property or diversifying revenue can require investment. The relevant question is whether the expenditure improves sustainable future economic benefits relative to the risk and capital involved.
Common Business Valuation Multiple Mistakes
Treating an Industry Multiple as the Valuation
An industry multiple can be a useful reference point, but it must match the earnings definition, size, risk, growth and transaction characteristics of the business being valued. A multiple without comparable evidence or business-specific analysis is a rule of thumb, not a complete valuation.
Maximising Short-Term Profit at the Expense of Business Value
Reducing training, maintenance, management or technology expenditure may temporarily improve profit while weakening capability and increasing future risk. Maintainable earnings should reflect the costs required to operate the business sustainably.
Assuming Every Dollar of Growth Adds Value
Growth adds value only when the expected return justifies the risk and investment. Low-margin growth that consumes working capital or depends on one customer may increase scale without producing a proportionate increase in value.
Confusing Book Value With Market Value
Book values are prepared under accounting rules and may reflect historical cost, depreciation and recognition criteria. They do not automatically represent current market value. Internally generated goodwill and other intangible assets may also be absent from the balance sheet.
Waiting Until a Buyer Is Already Negotiating
Once a transaction begins, there may be limited time to address owner dependence, weak records, concentration or contractual problems. An earlier valuation can identify which issues matter and provide time to respond.
When Should You Assess Your Business Value Drivers?
Business value drivers are worth assessing well before a sale. The exercise can be useful when:
- planning an ownership transition or succession;
- considering a sale, acquisition or management buyout;
- introducing or exiting a shareholder;
- preparing for investment or finance discussions;
- undertaking strategic planning;
- responding to a tax, legal or reporting requirement; or
- measuring whether operational improvements are translating into value.
Australian Government guidance recommends regularly calculating business value as part of succession planning because value can change materially before an owner leaves.
The appropriate valuation scope depends on the decision. An internal planning exercise, an indicative valuation and a comprehensive report prepared for tax or dispute purposes are not interchangeable. The asset, purpose, valuation date, intended users and required evidence should be defined before work begins.
Build a More Valuable—and More Transferable—Business
The strongest businesses do not merely produce profit. They produce earnings that are supportable, resilient, transferable and capable of generating appropriate returns on the capital required.
That is why business value drivers matter. They help explain the difference between the profit reported in the accounts and the value that a knowledgeable buyer or investor may attribute to the business.
IBV provides independent business valuations for Australian business owners, accountants, advisers and organisations. Each engagement begins by defining what is being valued, why the valuation is required, the relevant date and the appropriate scope of work.
Want to understand what is supporting—or constraining—the value of your business? Speak confidentially with IBV about an independent valuation and the evidence needed for your circumstances.
Editorial note: This article provides general information only. It does not constitute taxation, legal, financial or investment advice. The value of a business depends on the relevant asset, purpose, valuation date, evidence, assumptions and circumstances. Obtain advice from appropriately qualified professionals before acting.
Business Value Drivers FAQs
What Are the Main Value Drivers in a Business?
Important drivers include maintainable earnings, recurring revenue, customer diversification, low owner dependence, capable management, effective systems, credible growth, cash conversion and transferability. Their importance varies by business and valuation purpose.
Does Higher Profit Always Mean a Higher Business Valuation?
Not necessarily. Sustainable earnings generally support value, all else being equal, but risk, growth, capital requirements, debt and transferability also matter. A temporary increase achieved through underinvestment may not support a higher valuation.
How Do Business Value Drivers Affect a Valuation Multiple?
Stronger, more predictable and transferable earnings may support a higher multiple than riskier earnings, all else being equal. There is no fixed uplift for any individual value driver.
Can Reducing Owner Dependence Increase Business Value?
It can support value when earnings become more transferable and key-person risk falls. The effect depends on whether management, systems, relationships and knowledge can genuinely operate without the owner.
How Long Does It Take to Improve Business Value?
There is no universal timeframe. Documentation may improve quickly, while customer diversification, management development and a sustained earnings record can take years. Demonstrated results carry more weight than untested plans.
Is a Business Valuation the Same as a Value-Improvement Plan?
No. A valuation estimates value at a defined date for a defined purpose. A separate improvement plan can use its findings to prioritise management action.
Sources and Further Reading
- Australian Government, business.gov.au, Value your business.
- Australian Government, business.gov.au, Develop your succession plan.
- International Valuation Standards Council, International Valuation Standards—standards overview, including IVS 103 and IVS 200.
- Accounting Professional & Ethical Standards Board, APES 225 Valuation Services, revised October 2024; effective from 1 January 2025.