Key takeaways
Goodwill is the attractive force that brings in customers—beyond the identifiable assets.
The High Court in Murry described goodwill as the right to conduct a business in the way that attracted its custom. Australian law treats it as a single asset attached to the business; for valuation it may be estimated as a residual after reconciling the business value with identifiable net assets.
Goodwill is usually already inside an earnings valuation.
Where a business is valued on maintainable earnings, goodwill is generally already reflected in that value. Adding a separate goodwill amount without reconciliation counts the same value twice.
Personal goodwill may leave with the owner; business goodwill can transfer.
Location, brand, contracts, systems and staff relationships can transfer to a buyer. Custom attached to the owner's personal skill or relationships is at risk when the owner leaves.
Evidence decides how much goodwill a buyer will pay for.
Customer retention, contract terms, recurring revenue, staff depth, documented systems and lease security show whether earnings will continue. Statements about reputation without records carry little weight.
Some businesses have little or no goodwill.
If earnings only cover a fair return on assets and a commercial wage for the owner's work, there may be no goodwill. Reducing owner dependence over time is the most reliable way to build it.
What goodwill actually is
In everyday conversation, goodwill means reputation. In valuation and law it has a more precise meaning. The High Court described goodwill in FCT v Murry (1998) as the legal right or privilege to conduct a business in substantially the same manner and by the same means that attracted custom to it—in other words, the attractive force that brings in customers and earnings beyond the value of the identifiable assets.
For Australian tax purposes, the ATO's Taxation Ruling TR 1999/16 describes goodwill as a single, indivisible asset attached to the business, distinct from the individual assets and circumstances that generate it. Accounting standards take a narrower, transaction-specific view: AASB 3 Business Combinations recognises goodwill in an acquisition as a residual based on the consideration and the identifiable net assets, under specific accounting rules. That accounting calculation is not a universal formula for every business valuation. For valuation purposes, goodwill may be estimated as a residual after appropriately reconciling the value of the business with its identifiable net assets and any separately valued intangibles such as contracts, licences or brands.
That definition matters because it explains why goodwill is usually not an extra amount added on top of an earnings-based valuation. If you value a business on its maintainable earnings, the goodwill is already inside that number.
Where goodwill comes from
The Murry decision identified several sources of goodwill, which remain a useful practical checklist:
These are sources of goodwill, not separate goodwill assets—for capital gains tax purposes the goodwill of a business is a single asset. What matters for value is whether the economic benefits each source generates are likely to continue after a transfer. A lease or a brand name can change hands without the custom following, so transferability is a question of evidence, not of labels. Personal goodwill—custom attracted by the owner's own skill and relationships—remains the hardest case.
Site goodwill — custom attracted by the location, such as a pharmacy in a busy shopping centre.
Name and brand goodwill — custom attracted by the business name, reputation or marketing.
Personal goodwill — custom attracted by the skill, relationships or personality of the owner.
Systems and staff — custom held by documented processes, trained employees and service standards.
Exclusive rights — licences, franchises or contracts that limit competition.
Transferable goodwill versus personal goodwill
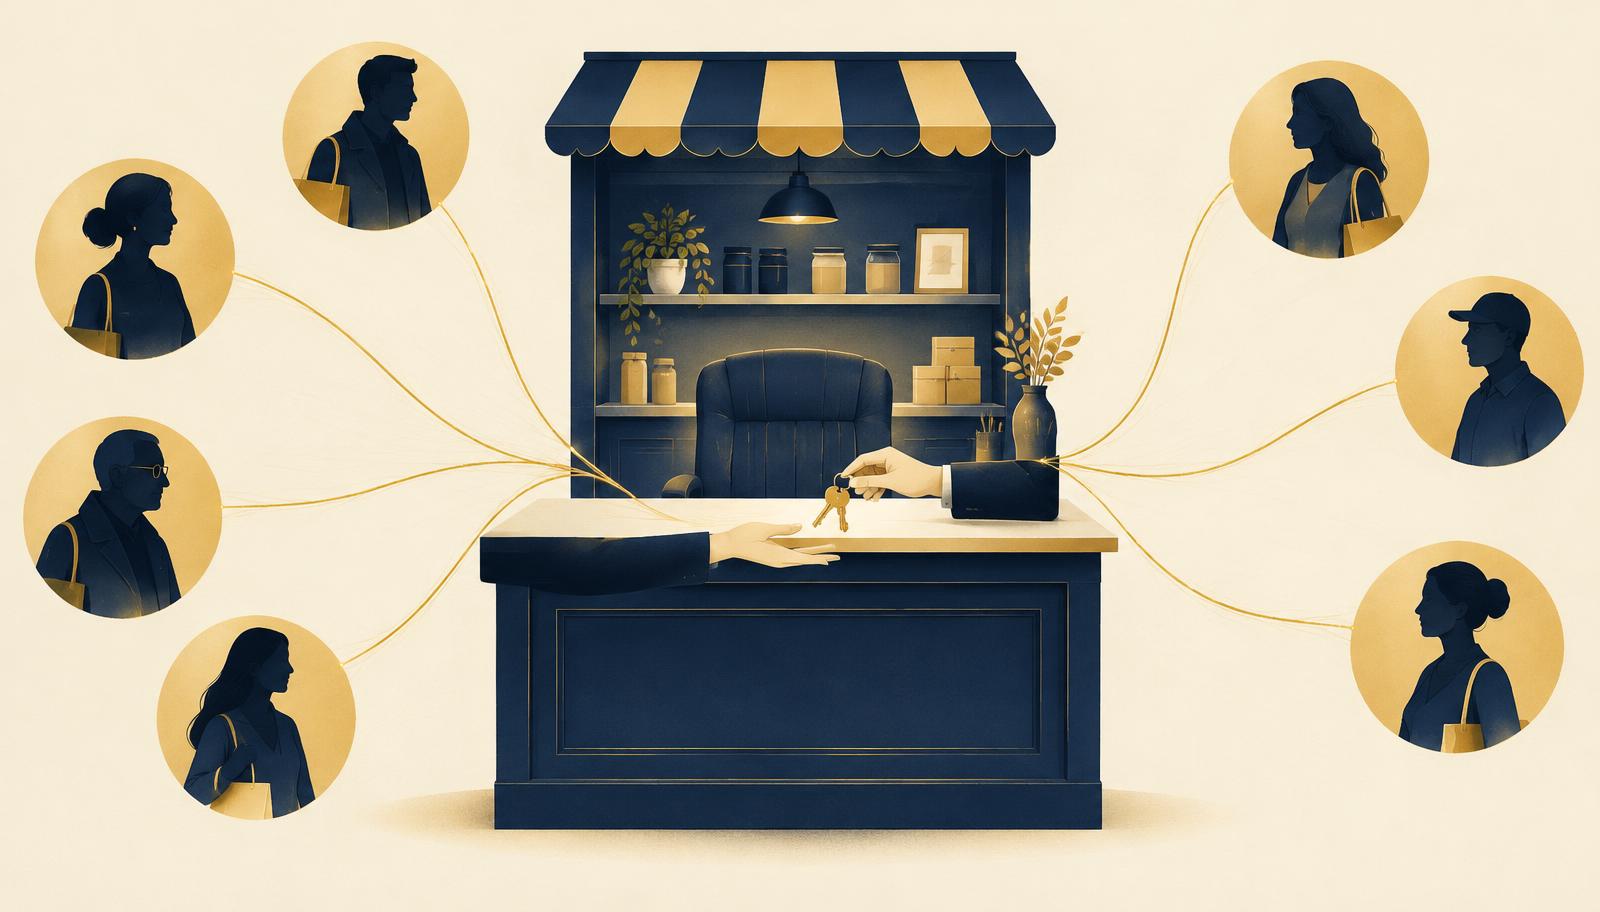
A buyer pays for earnings they can expect to keep. Goodwill attached to the business—its location, systems, contracts, team and brand—can transfer. Goodwill attached to the person—their trade skills, personal relationships and reputation—may walk out the door with them.
Consider two fictional accounting practices with identical fees. In the first, the founding partner personally manages every client, signs every return and handles all new enquiries. In the second, client managers own the relationships, work is documented in practice software and the founder mainly reviews. A buyer of the second practice can reasonably expect most clients to stay. A buyer of the first faces real risk that clients will follow the founder or leave during transition. Our accounting practice valuation page explores this in detail; the same logic applies to medical, trade and professional firms.

Signed
A clear valuation conclusion starts with an agreed purpose, relevant evidence and disclosed assumptions. The report identifies the interest valued and explains the reasoning behind its conclusion.
How goodwill is valued in practice
Goodwill may be assessed directly or derived as a residual, depending on the valuation purpose and methodology. Where a business is valued on its maintainable earnings, the economic contribution of goodwill is generally already reflected in that operating value—adding a separate goodwill amount on top, without an appropriate reconciliation, would count the same value twice. Where a residual is used, goodwill is the business value less the value of net tangible assets and any separately identified intangibles, with each component reconciled so nothing is counted twice.
Owner dependence is addressed in that process, not afterwards. It may affect the earnings expected to continue, the risk applied to those earnings, the terms a buyer would require (such as a longer handover or an earn-out), or all three. A valuer explains which approach has been taken and why, so the same risk is not counted twice. Our explanation of business valuation methods shows how earnings, asset and market approaches fit together.
The evidence that supports transferable goodwill
Goodwill is persuasive only when it can be evidenced. The records that carry most weight include:
Customer retention and concentration — how long customers stay and how much revenue depends on the top few.
Contracts and their terms — renewal dates, assignment clauses and change-of-control rights.
Recurring revenue — subscriptions, service agreements and repeat-order patterns.
Staff depth — who holds key relationships, licences and technical knowledge, and whether they are likely to stay.
Documented systems — procedures, pricing tools and software that allow the business to run without the owner.
Lease security — remaining term and options for businesses dependent on location.
Online presence — domain names, reviews and directory listings owned by the business rather than the individual.
A worked example of goodwill as a residual (fictional figures)
Assume a fictional debt-free plumbing business is valued at $900,000 on a going-concern basis, with normalised maintainable earnings supporting that figure. Illustrative figures only.
These components are assumed to be separately valued without overlap—so the working-capital figure excludes the stock already listed. The identified components total $380,000, leaving residual goodwill of $520,000: the part of the value explained by the business's reputation, customer base, systems and team rather than by anything that can be listed on an asset register.
Now suppose most of the residential customers call the owner's personal mobile, and the two senior plumbers have indicated they may leave on a sale. A buyer would reasonably expect some of those earnings to fall away, or would require a long handover and part of the price deferred. The maintainable earnings, and therefore the business value, would be lower—and so would the goodwill, even though nothing on the asset register changed. That is how owner dependence flows through a goodwill valuation: through the earnings and risk, not as a separate deduction from a fixed goodwill figure.
Vehicles, tools and equipment at market value: $210,000
Stock at cost, adjusted for obsolete items: $40,000
Other net operating working capital (excluding stock): $50,000
Separately identified intangible: a three-year maintenance contract with a body corporate group, valued at $80,000
Goodwill in franchises and licensed businesses
In franchised businesses, part of the goodwill belongs to the franchise system—the brand, supply arrangements and marketing—and the franchisee's interest depends on the remaining term, renewal rights and the franchisor's transfer conditions. In licensed businesses such as pharmacies, childcare or liquor, goodwill may depend on licences that cannot simply be assumed to transfer. In both cases the agreements and approvals are part of the goodwill evidence. Our franchise valuation page sets out what to provide.
Common goodwill mistakes
Adding goodwill on top of an earnings valuation. This counts the same value twice.
Calculating goodwill as "one year's turnover". Rules of thumb ignore margins, risk and transferability.
Ignoring owner dependence. A business whose profit relies on the owner's personal relationships cannot be valued as though those relationships are guaranteed to transfer.
Assuming goodwill always exists. If a business earns no more than a fair return on its tangible assets and a commercial wage for the owner's work, there may be little or no goodwill at all.
Why goodwill matters for tax and family law
Goodwill is a CGT asset, and its value can affect small business CGT concessions, restructures and related-party transfers. The ATO's market valuation guidance expects goodwill and other intangibles to be valued with a clear method and evidence. In property settlements, the treatment of personal goodwill is often debated, because some of the value may depend on a party's future personal effort. In both contexts, an explained, evidenced position is what holds up. Our goodwill and intangible asset valuation service covers these situations.
How to strengthen transferable goodwill before a sale
Owners who plan two or three years ahead can materially improve transferability: introduce key clients to staff, document processes, put customer arrangements into written contracts, extend the lease, move domain names and reviews into the business's name, and reduce the share of revenue that depends on the owner personally. None of these steps guarantees a price, but each gives a buyer—and a valuer—evidence that the earnings will continue. If you are starting that process, our guide to selling a business sets out the preparation in order, and our Fixed Professional Fees page explains how to commission a valuation to measure your starting point.
Frequently asked questions
What is goodwill in a business valuation?
Goodwill is the economic benefit arising from a business's ability to attract and retain customers. Australian law recognises it as a single asset attached to the business, distinct from the assets and relationships that generate it. For valuation it may be estimated as a residual after reconciling the business value with its identifiable net assets and separately valued intangibles.
How is goodwill calculated?
Goodwill may be assessed directly or derived as a residual, depending on the purpose and methodology. Where a residual is used, it is the business value less net tangible assets and separately identified intangibles, with each component reconciled so nothing is counted twice. There is no single formula that applies to every valuation.
Source: AASB 3 Business Combinations
What is the difference between personal and business goodwill?
Business goodwill attaches to the enterprise—its location, brand, systems and contracts—and can transfer to a buyer. Personal goodwill attaches to the owner's skills, reputation and relationships and may not transfer when the owner leaves.
Is goodwill worth one year's turnover?
No reliable rule of that kind exists. Turnover ignores margins, owner costs, risk and transferability. Two businesses with the same turnover can have very different goodwill, or none at all.
Can a business have no goodwill?
Yes. If the business earns no more than a fair return on its tangible assets plus a commercial wage for the work the owner performs, there may be little or no goodwill to value.
Does goodwill get added to the value of the business?
Generally no. An earnings-based valuation already includes goodwill. Adding it separately counts the same value twice. Goodwill is identified within the conclusion, not added to it.
How does owner dependence affect goodwill?
Heavy reliance on the owner increases the risk that customers and earnings will not continue. That may reduce expected earnings, increase the risk applied to them, or require handover and earn-out terms in a sale.
Is goodwill a CGT asset?
Yes. Goodwill is a CGT asset, and its market value can matter for small business CGT concessions, restructures and transfers between related parties. The ATO expects a supportable method and evidence.
Source: ATO: Market valuation of assets
How is personal goodwill treated in family law?
It is often debated, because part of the value may depend on a party's future personal effort. How it is treated depends on the facts and legal advice. A valuation should clearly separate transferable and personal elements so advisers can apply the law.
Source: Federal Circuit and Family Court: Financial or property matters
How can I increase transferable goodwill before selling?
Introduce staff to key clients, document systems, formalise customer contracts, secure the lease, put domains and online reviews in the business's name and reduce revenue that depends on you personally. These steps give buyers evidence that earnings will continue.

A clear, independent view of value — with the evidence behind it.
- Understand the conclusion — and what drives value.
- Gain an independent perspective. Move forward with confidence.
- Benchmark your business against industry performance.
- Identify strengths, risks and opportunities through SWOT analysis.
WHAT YOU GET IN A LIMITED SCOPE VALUATION REPORT
Inside your IBV™ report
Executive Summary
Conclusion of value · Method selected · Valuer qualifications
Detailed Report
Maintainable earnings · Cap rate / multiple · Premise of value
The Evidence Pack
SWOT analysis · Top Performers Report · RAVDA score
APES 225 voluntarily aligned. Report depth and supporting analysis follow your agreed package and engagement scope.
Free Valuation Call