BUSINESS VALUATION INSIGHTS
Why comparable profits do not necessarily produce comparable business values—and what owners can do about it.
Why the Same Profit Can Produce a Different Business Valuation
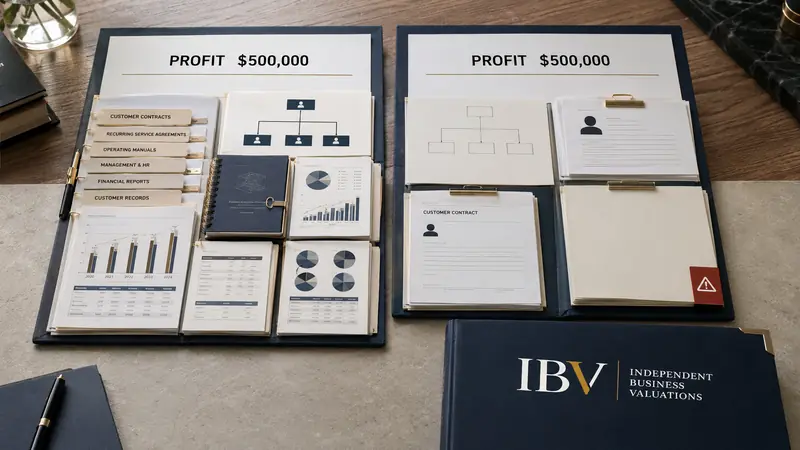
Imagine two businesses each reporting $500,000 in annual profit. One has recurring revenue, a capable management team, documented systems and hundreds of customers. The other depends on its owner, earns half its revenue from one client and operates through knowledge held in a few people’s heads.
The profit figure is the same. The economic proposition is not.
A professional business valuation does not simply attach an industry multiple to the latest profit number. It considers the earnings or cash flow available to an owner, the risk that those returns may not continue, the investment required to produce them and the extent to which the business can transfer to another owner.
| The central principle: Value is influenced not only by how much a business earns, but by the quality, durability and transferability of those earnings. |
How Business Value Drivers Affect a Valuation
Business value drivers are the operational, financial and strategic characteristics that influence expected future returns and risk. Their effect may appear in different parts of a valuation:
- the assessment of maintainable earnings or cash flow;
- forecasts and the assumptions supporting them;
- the capitalisation rate, discount rate or valuation multiple;
- surplus assets, debt and working-capital adjustments; or
- the weight placed on different valuation methods.
There is no universal scorecard and no fixed uplift for improving a single driver. The drivers interact, and their relevance depends on the business, industry, valuation date, purpose and standard of value.
1. Quality of Earnings
Reported accounting profit is the starting point—not necessarily the amount used in a valuation. A valuer may examine whether earnings include non-recurring income or expenses, owner-specific costs, unusual transactions, related-party arrangements or accounting choices that do not reflect ongoing operations.
A business with stable, supportable maintainable earnings will usually present a stronger valuation case than one whose profit relies on one-off events or aggressive adjustments. Owners should expect proposed normalisation adjustments to be tested against evidence rather than accepted at face value.
2. Recurring and Predictable Revenue
Revenue that repeats under subscriptions, service agreements, maintenance programs or established customer behaviour can improve visibility over future cash flow. That does not make every recurring dollar equally valuable: contract duration, cancellation rights, renewal history, pricing power and the cost of serving the revenue still matter.
A business that must win every sale again next month may be riskier than one with demonstrated repeat demand—even where their current profits are identical.
3. Customer Concentration
A large customer can be an asset and a vulnerability. If losing one customer would materially reduce revenue or profit, a prospective owner inherits concentration risk.
The analysis should go beyond a percentage of revenue. It may consider contract terms, customer tenure, switching costs, relationship ownership, pipeline strength and how readily lost work could be replaced. A diversified customer base can make earnings more resilient, but diversification without customer quality is not automatically valuable.
4. Dependence on the Owner
A profitable business may be difficult to transfer if the owner personally controls sales, technical delivery, supplier relationships, pricing and key decisions. A buyer may ask whether the earnings will continue when that owner steps away—and what it would cost to replace their work.
Reducing owner dependence does not mean making the owner irrelevant. It means converting personal capability into organisational capability through delegated authority, retained management, documented relationships and repeatable processes.
5. Management Depth and Workforce Stability
A capable team can protect continuity and make growth less dependent on one person. Relevant considerations include the depth of management, employee tenure, key-person exposure, remuneration, retention arrangements, succession coverage and whether essential skills are realistically replaceable.
A large workforce is not inherently a value driver. What matters is whether the people structure supports the expected earnings and can continue through a change of ownership.
6. Systems, Processes and Reliable Information
Documented operating procedures, appropriate controls and dependable management reporting help a business perform consistently and allow another owner to understand it. They also improve the evidence available for valuation.
Systems create value when they genuinely reduce errors, protect margins, support scale or preserve institutional knowledge. A folder of outdated procedures or software that the team does not use will not achieve the same result.
7. Competitive Position and Barriers to Entry
A business may earn superior returns because of its reputation, specialised capability, location, licences, intellectual property, customer relationships, data or network effects. The valuation question is whether that advantage is real, defensible and transferable.
Claims such as “we have the best service” require support. Evidence might include retention, win rates, pricing, margins, protected rights, referral strength or performance relative to competitors.
8. Growth Prospects—and the Evidence Behind Them
Growth can add value when it is commercially plausible and produces adequate returns. A forecast based only on ambition is not equivalent to a forecast supported by capacity, demand, signed contracts, a qualified pipeline, market evidence and a credible execution plan.
Growth may also consume working capital, staff, equipment and management attention. A valuation should consider the investment and risk required to achieve it, not merely the projected revenue.
9. Margins, Cash Conversion and Working Capital
Two businesses can report the same profit but convert very different amounts into cash. Slow collections, large inventory holdings, customer prepayments, supplier terms and seasonal funding needs can materially change the economics for an owner.
Working capital is also a transaction issue. The amount required to operate the business at a normal level may affect the equity value or the completion mechanism, depending on the valuation purpose and transaction terms.
10. Capital Expenditure and Asset Condition
Current profit may overstate economic performance if the business has deferred essential maintenance or requires significant expenditure to sustain operations. Conversely, recent investment in productive capacity may support future earnings—provided demand and returns justify it.
A valuer may distinguish the assets needed for normal operations from surplus or non-operating assets. Asset ownership, lease commitments and replacement cycles therefore need to be understood rather than inferred from the profit and loss statement.
11. Financial Records and Forecast Credibility
Reliable financial information does not create the underlying earnings, but it makes them easier to test and defend. Inconsistent classifications, unexplained adjustments and gaps between financial statements, tax records and management accounts can increase uncertainty.
Good records should allow a valuer to reconcile historical performance, understand drivers of change and assess assumptions. This is especially important where management asks the valuer to rely on a forecast or normalised earnings figure.
12. Transferability, Legal Rights and Business-Specific Risk
Ultimately, value depends on what can transfer and continue. Contracts may require consent. Licences may attach to an individual. Intellectual property may not be properly owned. A lease may be short or restrictive. A supplier arrangement may be informal. Litigation, compliance failures, cybersecurity exposure or environmental obligations may also affect risk.
These issues do not always destroy value, but they can change assumptions, reduce certainty or require specific valuation adjustments. Discovering them early gives an owner more options than discovering them during valuation or buyer due diligence.
Which Business Value Drivers Matter Most?
The answer depends on where value is concentrated. For a professional practice, owner dependence and client relationships may dominate. For a manufacturer, plant condition, capacity and customer concentration may be critical. For a subscription business, retention, recurring revenue economics and technology ownership may carry more weight.
The most useful question is not “Which of the 12 boxes can we tick?” It is:
| Ask this: What could cause the expected future cash flow of this particular business to be higher, lower or less certain—and would that factor remain after a change of ownership? |
How Business Owners Can Strengthen Value Before a Valuation
Value improvement is usually a program, not a cosmetic exercise immediately before sale. A practical starting point is to:
- reconcile and explain at least several years of financial performance;
- identify non-recurring and owner-specific items with supporting evidence;
- measure customer, supplier and employee concentration;
- document key processes, responsibilities, contracts and intellectual property ownership;
- test forecasts against capacity, cash requirements and historical accuracy;
- develop management capability beyond the owner; and
- address material legal, operational and compliance risks before they become transaction issues.
Not every improvement will increase value by more than it costs. Priorities should be set according to the business, the owner’s timeframe and the likely purpose of the valuation.
Why an Independent Business Valuation Matters
Owners are naturally close to what they have built. That knowledge is valuable, but it can also make it difficult to distinguish effort, potential and personal importance from market value.
An independent valuation provides a structured assessment of the evidence, assumptions, earnings, risks and valuation methods relevant at a defined date and for a defined purpose. It can also show which claimed value drivers are already reflected in the financial performance—and which require stronger evidence.
The objective is not to produce the highest possible number. It is to produce a conclusion that is supportable, understandable and fit for its intended use.
The Bottom Line: Profit Is Only Part of the Value Story
Profit matters. But the same profit can support a different value when its quality, predictability, capital requirements, risk or transferability differs.
Business owners who understand these drivers can make better decisions about succession, sale preparation, ownership changes, tax planning and growth. More importantly, they can approach a valuation with evidence rather than assumptions.
If you need to understand what your business is worth—and why—Independent Business Valuations provides fixed-fee, evidence-based business valuation services to business owners and advisers Australia-wide.
| Speak confidentially with IBV: Discuss the purpose of your valuation, the business interest to be valued and the evidence needed to support a clear, defensible conclusion. |
Frequently Asked Questions About Business Value Drivers
What are the main drivers of business value?
The main drivers commonly include maintainable earnings, recurring revenue, customer concentration, owner dependence, management depth, competitive position, growth prospects, cash conversion, capital requirements, financial information and transferability. Their importance varies by business.
Does increasing profit always increase business value?
Not automatically. Higher sustainable earnings can support a higher value, but the source, durability and risk of those earnings matter. Growth that requires excessive capital or depends on one customer may not create the expected value.
Can reducing owner dependence increase business value?
It can strengthen transferability and reduce risk where the business currently depends on the owner for essential relationships, knowledge or delivery. The valuation effect depends on the facts and whether the changes genuinely protect future earnings.
How long does it take to improve business value?
Some issues can be corrected quickly, such as documenting intellectual property ownership or improving financial reconciliations. Others—such as diversifying customers, building management depth or establishing recurring revenue—may require years.
Is a business valuation the same as a sale price?
No. A valuation is an estimate of value prepared for a defined purpose, date, standard and premise. A transaction price may also reflect negotiation, deal structure, buyer-specific synergies, finance, tax, warranties and market conditions.
Sources and Technical Basis
- Australian Taxation Office, Market valuation for tax purposes
- Accounting Professional & Ethical Standards Board, APES 225 Valuation Services (October 2024)
- International Valuation Standards Council, International Valuation Standards
Editorial note: This article provides general information only. It is not legal, tax or financial advice. The effect of any value driver depends on the valuation purpose, date, standard of value, available evidence and the specific facts of the business.