
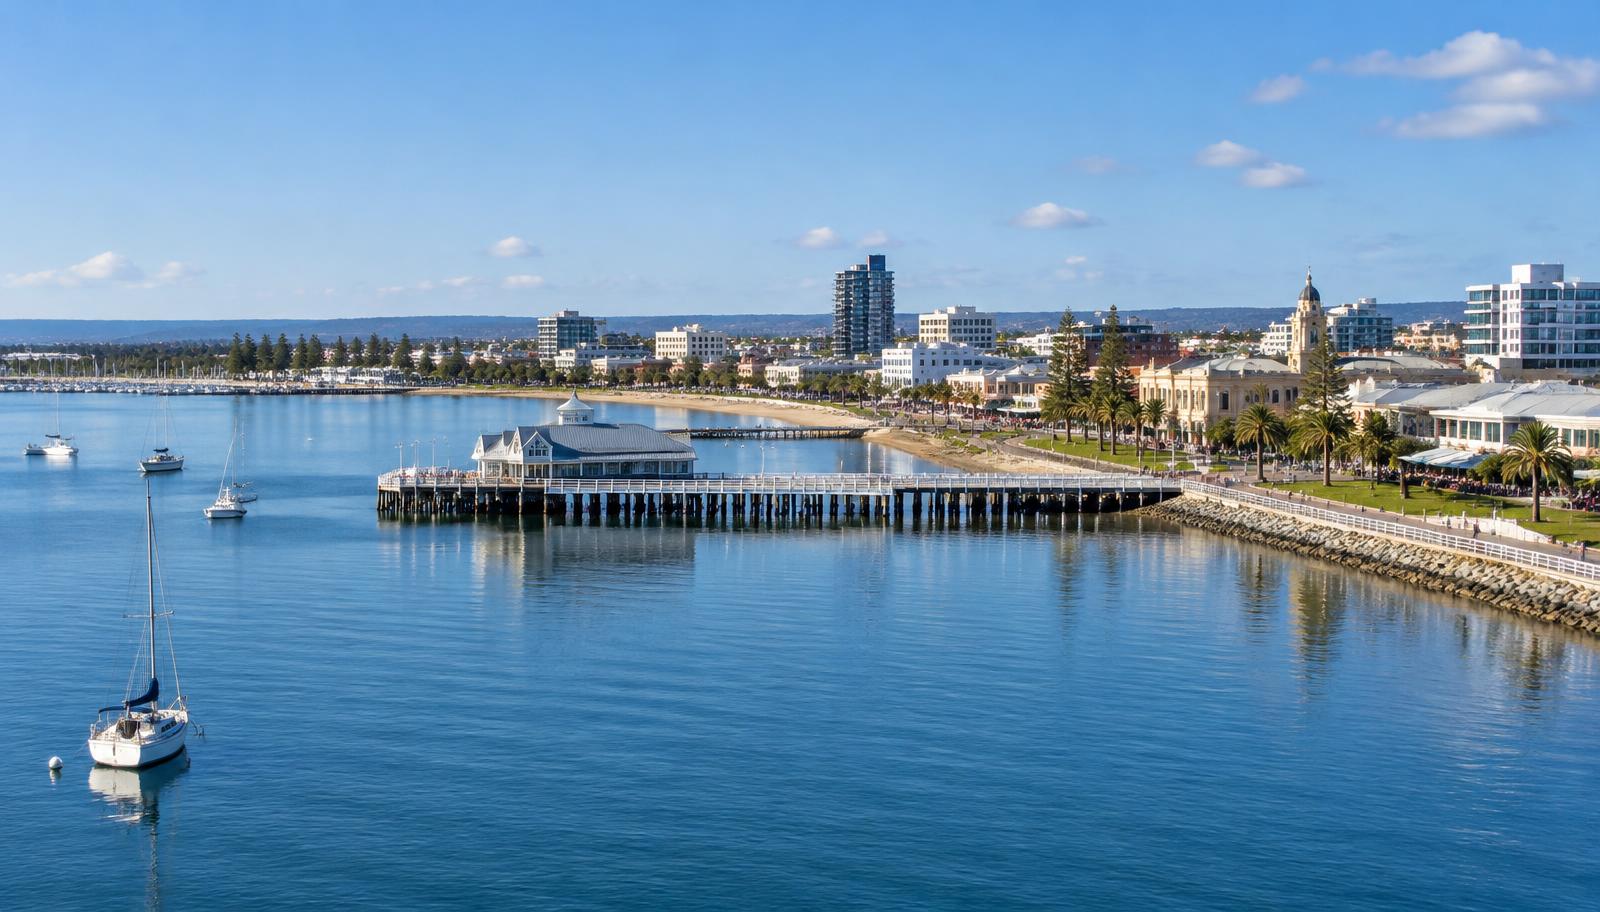
Independent valuations for Geelong ownership decisions
When you sell a business, bring in a partner or organise succession, a useful valuation must explain more than a headline number. IBV™ assesses the identified business or ownership interest at the agreed date, with the purpose and intended users established before work starts. Geelong owners receive a reasoned conclusion based on their own evidence, not a generic regional multiplier.
Your engagement is led by Dr Patrick Hillenbrand, AVI Certified Business Valuer. The signed report documents the methods, assumptions and material limitations. Our IBV™ Independence Guarantee means the professional fee is not tied to the value concluded. We are not bound by APES 225 but voluntarily adhere to its valuation guidance.
Understand the business behind the regional story
Greater Geelong's economic development material identifies opportunities across advanced manufacturing, health, the visitor economy, agribusiness and creative or digital activity. These sectors have different operating economics. A manufacturing supplier with specialised plant needs different analysis from a professional practice, waterfront hospitality venue or software business.
The council's sector priorities provide context, not evidence that your revenue will grow. We identify where customers come from, whether income recurs and which resources are necessary to deliver it. A local business may serve Geelong residents, institutional customers, Melbourne clients or interstate buyers; the actual customer mix matters more than the trading address.
Investment announcements and new precinct plans should be distinguished from contracts held by your business. Opportunities may warrant investigation, but they should not be treated as established earnings without support.
Examine manufacturing capability and replacement needs
For an engineering or manufacturing business, review orders, margins by product or job, major customer terms and supplier dependencies. Identify whether tooling, designs and technical knowledge belong to the business or remain with a customer or departing owner. Specialised capability is valuable only within the rights and practical capacity the business actually controls.
Consider an illustrative Geelong component manufacturer whose recent profit includes an unusually large order. Before treating that result as maintainable, check whether the order repeats, what production capacity it consumed and whether other work was displaced. A full order book does not necessarily mean higher sustainable margins.
Review equipment condition, maintenance history and replacement expenditure. Distinguish assets essential to current output from surplus items. An earnings-based conclusion may already reflect the productive use of equipment; adding a separate plant figure without reconciliation can double count value. If property is owned separately, identify the occupancy assumption and keep any specialist property assessment distinct from operating goodwill.

Signed
A clear valuation conclusion starts with an agreed purpose, relevant evidence and disclosed assumptions. The report identifies the interest valued and explains the reasoning behind its conclusion.
Test goodwill in practices and knowledge businesses
Health-related, professional and digital businesses can depend on relationships, specialist staff and intellectual property rather than a large asset base. Identify recurring client work, referral arrangements and the rights to use software, designs or other intellectual property. Examine whether agreements and registrations permit continuity after an ownership change; legal questions should be confirmed by the relevant adviser.
Separate personal reputation from business systems. If a founder generates work, oversees delivery and retains the important client relationships, historical profit may require a realistic allowance for replacement duties. Staff responsibilities, documented processes and retention evidence help explain whether the earnings are transferable.
For a project-based creative or technical business, distinguish contracted work from proposals and separate development spending from recurring operating needs. Not every historical expense is a legitimate add-back, and not every new product forecast represents proven demand.
Read visitor-facing trading over representative periods
Geelong hospitality and visitor-related businesses should be assessed using their own monthly performance, rather than assumptions about waterfront appeal or regional tourism. Compare busy and quiet periods, occupancy costs, staffing and event-related income. Establish whether a favourable period reflects recurring demand or an exceptional event.
Review lease terms, renewal options, fitout obligations and landlord consent issues with your solicitor. Prepare booking or sales records that reconcile to accounts. A purchaser needs to understand both the income opportunity and the obligations required to continue trading. Regional popularity does not resolve an expiring lease or explain an unusually low owner salary.
Prepare for the right valuation engagement
Provide recent financial statements, current management accounts, ownership records, major customer agreements, leases and an asset register. Explain unusual transactions, related-party charges and changes in operations. Where information is incomplete, flag the gaps early so we can discuss supporting evidence with you and your accountant.
Our business sale valuation service supports informed negotiation, not a guaranteed price. For an ownership transition, see estate and succession valuations. For CGT purposes, your tax adviser confirms the transaction, relevant date and required basis of value.
Fixed Professional Fees are agreed in advance: Calculated Value is $2,450 + GST for eligible personal planning only; Limited Scope Conclusion of Value is $4,950 + GST and is most common. Tax, family law and shareholder matters require at least Limited Scope. Full Conclusion is quoted on instructions. Fees are payable on signing. Calculated and Limited Scope generally take 5–7 business days after complete information and signed engagement; Full Conclusion timing is agreed individually.
We support Geelong remotely through document review and scheduled discussions, without a local office. IBV does not undertake expert-witness or court-appointed valuations. Tell us what decision your valuation must support.
Geelong business resources
Council business support
Greater Geelong business and investment provides local business, permit and investment information.
Sector and development context
Council's economic development update identifies sector opportunities; compare them with your actual trading evidence.
Preparing professional advice
Business Victoria: talk to a business adviser explains advice areas that can complement valuation preparation.
Regional investment connections
Regional Development Victoria: Regional Launching Pads offers regional investment and business connections, not business-specific valuation benchmarks.
Frequently asked questions
How is specialised equipment treated in a Geelong manufacturing valuation?
Identify ownership, condition, utilisation and replacement needs, then explain treatment under the selected method. Productive equipment may already contribute to an earnings-based value. Surplus assets and separately held property need distinct treatment so their value is not added twice.
Does an advanced-manufacturing label increase a Geelong business's value?
Not automatically. Verify the business's actual capability, commercial rights, customer agreements and earnings. A council sector priority or regional investment initiative does not establish a premium for an individual manufacturer or demonstrate secured demand.
What if a Geelong factory's profit includes one large order?
Compare the order with normal trading, assess whether it recurs and identify capacity or costs required to deliver it. Explain whether recent profit represents sustainable performance or an exceptional period. An order book and its delivery requirements should be assessed together.
Can tooling or designs belonging to a Geelong customer count as business assets?
Do not assume ownership. Review contracts and the asset records to establish who controls the tooling, designs and rights to use them. Customer-owned assets may support current production without being property the business can transfer to a purchaser.
How is goodwill assessed in a Geelong professional practice?
Review recurring fees, client retention, staff responsibilities and the owner's role in generating and delivering work. Distinguish personal reputation from relationships supported by business systems. Historical earnings need realistic allowance for duties that must continue after a transfer.
Are Geelong software prototypes or research projects automatically valuable?
No. Establish commercial rights, development obligations, customer demand and evidence of income or other supportable benefits. Promising technology or an institutional collaboration is not the same as a profitable, transferable commercial contract.
How do Geelong hospitality leases affect a valuation?
Review the term, options, occupancy costs, fitout obligations and consent requirements. Your solicitor should confirm legal continuity. A waterfront location or strong seasonal sales does not resolve an expiring lease, and valuation assumptions should disclose material occupancy uncertainties.
Should a Geelong owner's unpaid work be reflected in costs?
Where the work must continue, assess what resources and reasonable replacement costs are required. Identify duties already undertaken by employees to avoid charging twice. A business is not more profitable simply because necessary family or owner labour has not been paid commercially.
Does IBV undertake Geelong valuations remotely?
Yes. Geelong owners work with Dr Patrick Hillenbrand through document review and scheduled discussions; IBV has no Geelong office. Evidence requirements and any additional specialist work are agreed in scope. Expert-witness and court-appointed valuations are not offered.
What should my adviser confirm for a Geelong CGT valuation?
Confirm the transaction, entity or interest, valuation date and required basis of value. Supply the relevant ownership and financial evidence. Tax-purpose valuations require at least Limited Scope; a valuation supports the evidence but does not itself determine concession eligibility or guarantee ATO acceptance.

A clear, independent view of value — with the evidence behind it.
- Understand the conclusion — and what drives value.
- Gain an independent perspective. Move forward with confidence.
- Benchmark your business against industry performance.
- Identify strengths, risks and opportunities through SWOT analysis.
WHAT YOU GET IN A LIMITED SCOPE VALUATION REPORT
Inside your IBV™ report
Executive Summary
Conclusion of value · Method selected · Valuer qualifications
Detailed Report
Maintainable earnings · Cap rate / multiple · Premise of value
The Evidence Pack
SWOT analysis · Top Performers Report · RAVDA score
APES 225 voluntarily aligned. Report depth and supporting analysis follow your agreed package and engagement scope.
Free Valuation Call
